Loading article...

Robinhood CEO Vlad Tenev says companies should control shareholder rights but should not be able to block separate token instruments tied to freely transferable shares, responding to AMC CEO Adam Aron's objections to AMC-linked tokens.
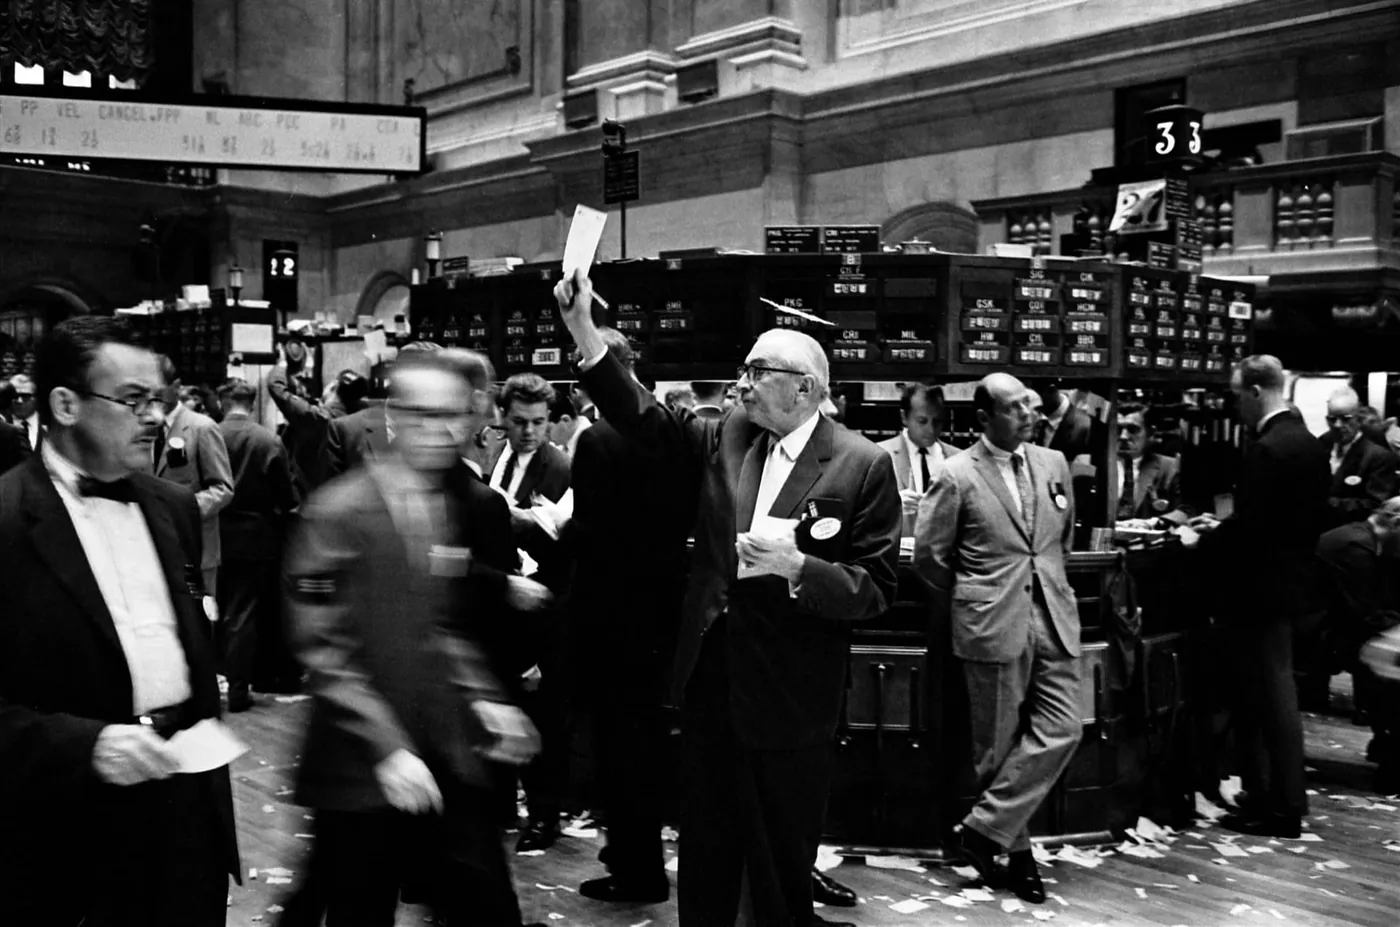
Stock brokers on the New York Stock Exchange floor. Photo: Library of Congress via Wikimedia Commons (public domain). Source
Robinhood chief executive Vlad Tenev said companies should not have a general right to approve or block third-party token instruments tied to their shares. "A company should control the rights attached to its shares, not every lawful use of those shares once they're in investors' hands," he wrote. "Going onchain shouldn't give the issuer a veto it never had offchain." The company controls the rights on its stock, he argued, while owners of freely transferable shares should generally decide how they hold and use them, in his Sept. 11 post.
The statement answers AMC Entertainment chief executive Adam Aron, who had called on Robinhood to stop trading AMC-linked tokens. Aron called the product a "fictitious synthetic equity market," said it could weaken a company's ability to raise capital, and said token holders own no AMC shares and receive none of the rights of share ownership. He said AMC had asked outside securities lawyers whether it could force Robinhood to stop and would put the question to the Securities and Exchange Commission.
Tenev laid out three ways a stock can meet a blockchain: the company itself issues shares onchain, an intermediary tokenizes custody of the shares, or an independent firm issues a separate security backed by or linked to them. Robinhood uses the third model. Its tokens are separately issued instruments backed one-for-one by underlying shares, giving economic exposure without touching the issuer's capitalization table, shareholder register, or the rights on its shares, he wrote. Those are Robinhood's descriptions, not a regulatory finding.
His test for when an issuer gets a say cuts both ways. "If a product purports to change the rights attached to the underlying shares, replaces the company's official stock ledger, or imposes new obligations on the company or its transfer agent, the issuer should be involved," Tenev wrote. But a separate instrument that holds or references freely transferable shares without doing any of that should not need issuer consent. He pointed to options, unsponsored ADRs, and structured products as existing instruments that reference shares without issuer control, CoinDesk noted. "Investors should know what they own, what rights it carries, and whether the issuer is involved," he added, saying Robinhood chose its model to cover many stocks and ETFs without each company rebuilding its own rails, and that it would adapt as guidance develops.
Tenev had previewed the argument two days earlier on television. "Issuers should have control and do have control over the rights and obligations of the stock that they issue, but that doesn't mean they control everything about it," he said on CNBC's Squawk Box on Sept. 9. "In particular, they don't control other companies issuing their own securities that reference those shares." Issuer consent depends on what exactly the product does, he said, and stock tokens should not automatically require it, CNBC reported. He described the tokens as debt securities backed by the underlying shares, with holders receiving dividends and economics but no vote, and said the company had not announced plans for the voting side.
Aron's side escalated first, and colorfully. In early September he said AMC had no involvement in, authorization of, or endorsement of the tokens, calling the product "contemptible" and "outrageous." "In good conscience, how can Robinhood as a U.S. company set up an operation in far offshore Jersey, an island 3000 miles away, and market a security sort of posing as AMC in some shape or fashion, and not comply with U.S. securities laws. That is shocking and shameful," he said, per Business Insider. "Your setting up some kind of fictitious synthetic equity market decouples stock token ownership from a company's ability to control its own capital raising efforts," he added. "This quasi-fake market you are creating on the island of Jersey sows distrust amongst the public about financial markets in general." His demand post told Robinhood to "cease and decist" trading AMC tokens, misspelling desist, a flourish he later said was deliberate humor. When Tenev replied to ask what the concern was, Aron pointed at the offshore structure and U.S. law.
Robinhood's legal chief answered in kind. "We know a little something about the U.S. securities laws and will not 'DECIST.' Send your lawyers and we'll educate them," chief legal officer Dan Gallagher wrote on Sept. 4. Tenev reposted the reply with the line: "We stand behind Stock Tokens."
The product at issue dates to June 30, 2025, when Robinhood unveiled U.S. stock and ETF tokens for eligible European customers at Cannes: more than 200 tokens, zero commissions or spreads, dividend support, trading 24 hours a day five days a week, issued first on Arbitrum with a company-built Arbitrum-based Layer 2 to follow for round-the-clock trading, self-custody, and bridging. "Our latest offerings lay the groundwork for crypto to become the backbone of the global financial system," Tenev said then, Fortune reported. The launch also brought the first tokenized private companies, OpenAI and SpaceX, through a European app offering 5 euros to early onboarders, backed by $1 million in OpenAI exposure and $500,000 in SpaceX, CNBC reported. The stock jumped about 13 percent on the news.
The private-company tokens drew the first regulatory challenge. OpenAI said the tokens were not OpenAI equity, that it had not partnered with Robinhood, was not involved, and did not endorse the product, adding that any transfer of its equity needs its approval, which it had not given. Robinhood answered that buyers get indirect exposure through a special-purpose vehicle holding a stake. Lithuania's central bank, Robinhood's lead EU regulator for both the brokerage and crypto licenses, said it had contacted the company and awaited clarification on the structure and customer communications, noting it could judge legality only afterward and that information must be clear, fair, and not misleading, CNBC reported in July 2025.
The legal structure matters to both sides' claims. The tokens are debt securities issued by Robinhood Assets (Jersey) Limited, backed one-to-one with shares held through a U.S. custody partner. Holders sit nowhere on AMC's register, carry no vote and no ownership rights, receive dividends through adjustments, and face high-risk disclosures including possible total loss. The product is unregistered in the United States and barred there plus Canada, the United Kingdom, Switzerland, and other jurisdictions, crypto.news summarized. Industry executives split on whether that counts as tokenized equity: tokenized stock should mean the stock itself, one infrastructure chief executive argued, contrasting it with debt routed through a separate vehicle; another put it as "a token is not equity, but equity can be a token," adding that a holder off the official register holds no AMC share. One analytics chief executive pointed at an AMC-linked pair trading around 60 times its reference price, in CoinDesk's Sept. 4 account of the debate.
Regulators have sketched categories without settling this fight. SEC staff from three divisions said in January that third-party-linked tokens may be debt, equity, or security-based swaps depending on structure, views that carry no legal force. A September proposal on transfer agents using blockchains targets the authoritative register question but would not by itself make a token a share, crypto.news noted. As of Sept. 14, no court had ruled on issuer consent, no SEC enforcement over the AMC token had been announced, and no AMC lawsuit had been filed.
Neither executive's post resolves anything. Tenev said Robinhood could adapt its model as regulatory guidance develops; Aron said AMC would seek the SEC's attention and explore forcing Robinhood to stop. The dispute now sits where the Kalshi and prediction-market fights sit: waiting on regulators to say which old rules cover the new wrapper.