Loading article...

SEBI's Demat 2.0 pilot tests tokenised corporate-bond issuance, holding, settlement and servicing within India's existing regulated market infrastructure.
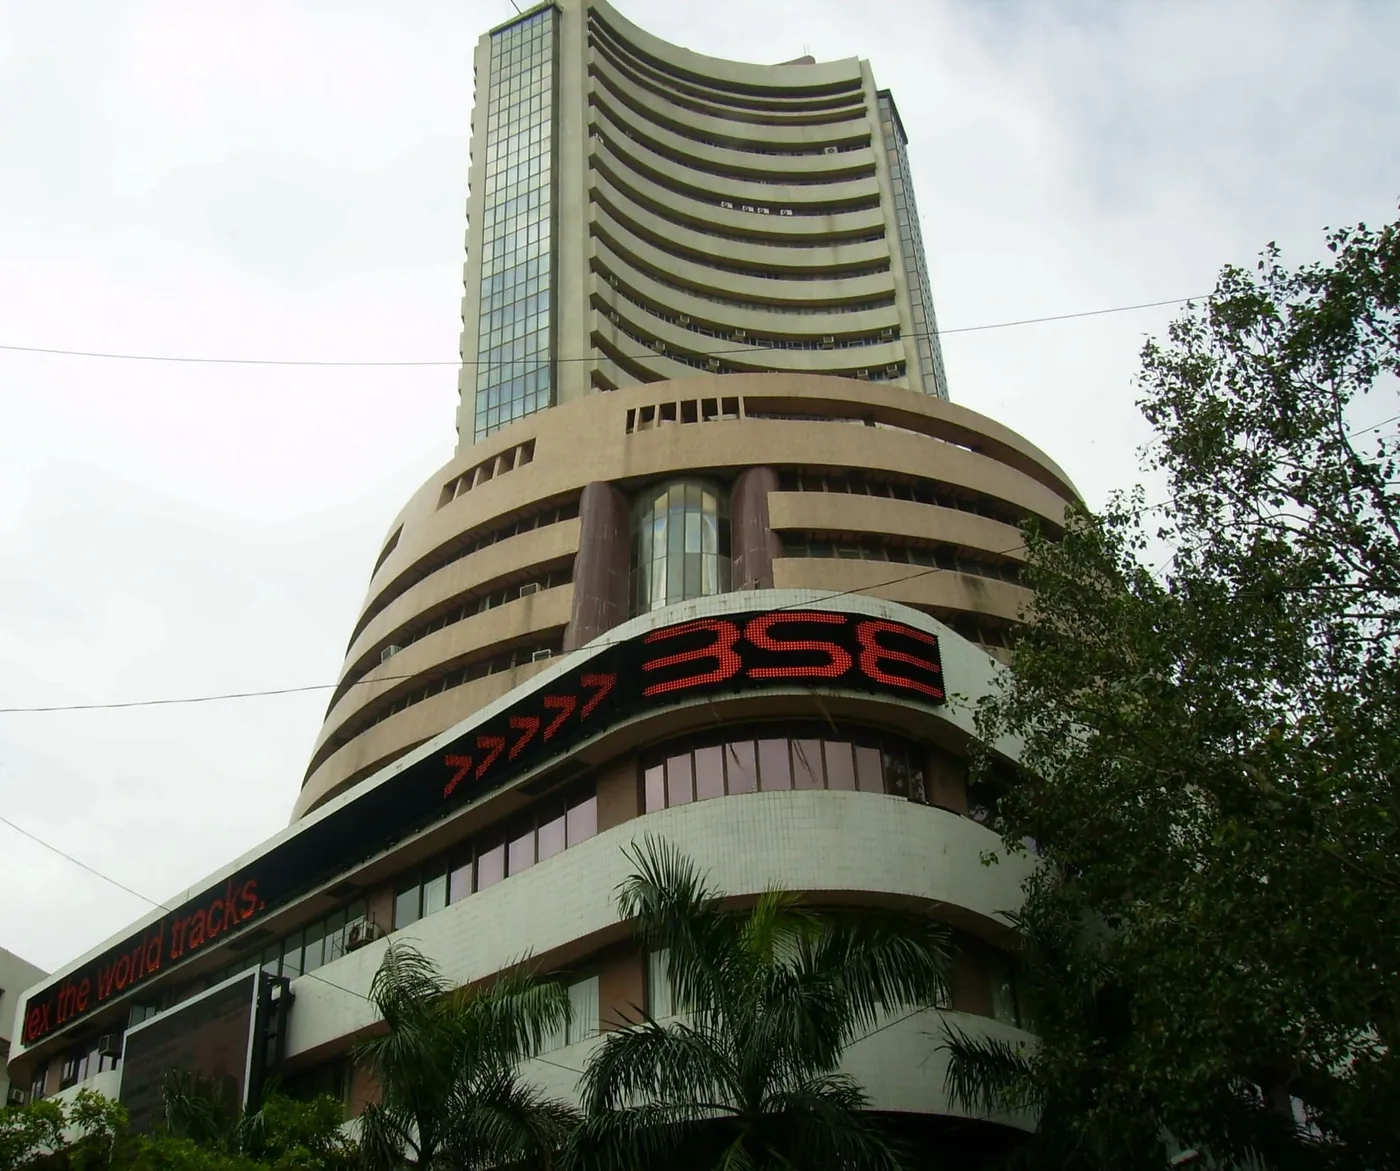
The Bombay Stock Exchange building on Dalal Street, Mumbai. Photo: Niyantha Shekhar via Wikimedia Commons (CC BY 2.0). Source
India's Securities and Exchange Board of India said on September 10 that it had successfully launched the Demat 2.0 pilot for tokenised corporate bonds. The brief SEBI release offers no transaction data or participant list. It directs readers to a detailed FAQ that describes a limited test of issuance, holding, trading and settlement on distributed-ledger technology, or DLT, rather than a new public market for tokenised assets.
The pilot issues the corporate bond itself as a native digital token on a private, permissioned ledger owned by the depositories, according to SEBI's FAQ. A permissioned network restricts who can operate or access it. In this case, it is not an open blockchain where anyone can run a node or move a token without the market infrastructure's controls.
SEBI describes Demat 2.0 as a next step in dematerialisation. The change under test is the technology used to maintain the ownership record and settle the transaction. It does not, by itself, create a new security or asset class. The FAQ says a tokenised corporate bond remains a security under the Securities Contracts (Regulation) Act, 1956 and stays subject to the applicable SEBI framework.
That distinction sets the boundaries of the experiment. The tokenised issue is to carry the same ISIN, the identifier assigned to a securities issue, as its corresponding bond. The issuer's coupon, maturity, covenants, rating, security and investor rights remain those of the bond, SEBI says. The regulator also says that tokenisation does not change the bond's legal character, rights, obligations or regulatory treatment. A digital token in this pilot is therefore the form in which the bond is issued and recorded, not a separate claim alongside it.
The issuance process remains tied to existing market systems. An issuer will use a stock exchange's Electronic Bidding Platform, or EBP, and obtain its ISIN from the depositories through the usual process, SEBI says. The ISIN will be flagged as a pilot or tokenised ISIN. Bidding, bid changes, cancellations and allotment deadlines are intended to remain unchanged.
After allotment, the depository is to credit the securities directly to successful investors' Demat 2.0 accounts. The issuer receives the proceeds in a central bank digital currency, or CBDC, wallet. For this pilot, CBDC means the e₹ used for the money side of the transaction. The FAQ says an issuer does not need a Demat 2.0 account, but does need a CBDC wallet linked to its designated bank account to receive issuance proceeds and, where relevant, pay coupons and principal at redemption.
The securities and funds legs are intended to settle atomically. That means the tokenised bond transfer and the CBDC transfer are one linked transaction: if one leg fails, the other does not settle. SEBI says this removes the interval in which one party could deliver securities without receiving payment, or pay without receiving the securities. The FAQ presents this as a pilot objective and an expected operational benefit, rather than evidence that the system has eliminated settlement risk in all circumstances.
The architecture does not remove the existing intermediaries. SEBI says market infrastructure institutions, or MIIs, are developing and operating the DLT infrastructure with technology and implementation support from NPCI. Initially, the depositories and stock exchanges will operate nodes. The FAQ says controlled access could later extend to other regulated entities as the pilot progresses, but it does not name prospective operators or give a date for that expansion.
The FAQ also says a separate tokenised exchange or segregated trading segment is not proposed. Existing request-for-quote, or RFQ, platforms and over-the-counter reporting platforms at stock exchanges are meant to be linked to the DLT infrastructure. Price discovery, order handling and reporting would remain in those channels, while the security and payment settlement legs are integrated with the tokenised infrastructure. SEBI has not announced that this secondary-market linkage is already available.
For an eligible investor, a Demat 2.0 account is an extension of an existing demat account, not a new account, SEBI says. The existing know-your-customer record is used. Registration is to take place through the depository's existing interface after the investor links an eligible demat account to a CBDC wallet and gives the required consent. The tokenised holding should remain visible in the existing depository interface and holding statement.
Participants also need a CBDC wallet with their own bank under the Reserve Bank of India's e₹ pilot, according to SEBI. The FAQ says no specialised DLT hardware, connectivity or separate technology investment is envisaged for issuers or investors. That does not mean all account holders can use Demat 2.0 now. Participation is limited by the pilot's stage, the relevant account and wallet arrangements, and the applicable investment rules.
Depositories, rather than investors, will hold and manage the Demat 2.0 account's private keys. Private keys are the cryptographic credentials used to control an address or account on a ledger. SEBI says investors will not need to manage those keys or obtain specialised ledger infrastructure themselves. This is a custody model run through the depository interface, not a model in which an investor independently controls a wallet's key material.
The FAQ places the depository at the center of the ownership record as well. It says the depository remains the authoritative record of beneficial ownership and that the ledger is the form in which that record is maintained for the pilot. The arrangement does not displace the depository's statutory role under the Depositories Act, 1996. A freeze, attachment or regulatory direction applying to a demat account, ISIN or token holding will also apply to the linked tokenised holding, SEBI says.
The legal and compliance rules for the underlying bond also continue. SEBI says requirements on credit ratings, debenture trustees, listing, disclosure, investment eligibility, valuation, classification and investor protection remain in force. A tokenised issue does not require a separate credit rating merely because of the ledger technology. Where a conventional dematerialised bond is a permitted investment, SEBI says the equivalent tokenised bond can also qualify, subject to the applicable rules.
The FAQ describes a three-stage rollout, using prospective language. Stage I is proposed to cover tokenised corporate-bond issuance through EBP integration and asset servicing on the ledger. Participation at that stage is initially expected to be institutional. SEBI has not published a list of eligible institutions, a comprehensive investor cap, a transaction cap, or a timetable for Stage I beyond the September 10 launch announcement.
Stage II is proposed to enable secondary-market trading and extend access to retail participants. Until that functionality is enabled, the FAQ says an interim peer-to-peer or demat-to-demat transfer may be enabled on request through the depositories. In that case, payment may occur outside the atomic settlement design through CBDC or normal banking channels. The FAQ says this is intended to provide an exit route, but it does not specify the approval process, pricing method, liquidity arrangements, fees or the conditions under which a requested transfer would be accepted.
Stage III could extend nodes to credit rating agencies, depository participants and other regulated entities. It also contemplates other instruments and a broader range of corporate actions. Those are potential later additions, not announced features. SEBI's materials do not give dates for either later stage, say which instruments could be added, or state whether the pilot will become a market-wide programme.
The bond terms can be encoded in a smart contract, which SEBI describes as software that can execute scheduled actions using the holdings recorded on the ledger at the relevant record date. The FAQ says coupons, redemptions and other scheduled corporate actions can therefore be executed automatically. It frames that outcome as a way to reduce repeated manual instructions and reconciliation. It does not publish the contract code, audit results, exception-handling rules, service-level targets or a production-governance framework.
The FAQ says the pilot will test smart-contract servicing and exception handling, regulatory controls and restrictions, cybersecurity, scalability, resilience, auditability, settlement finality and the roles of MIIs. These are testing objectives. SEBI has not released pilot performance data on any of them, so the release does not establish that the system has met those objectives at scale.
SEBI is running Demat 2.0 through its Regulatory Sandbox. The FAQ says any necessary specific relaxation would be given within that sandbox for a defined scope and period. It also says the pilot is meant to test the architecture and operating arrangements before a broader regulatory framework is considered. That leaves the existing securities regime in place for the bond while reserving any pilot-specific exceptions for the sandbox process.
SEBI's official announcement and FAQ do not identify bond issuers or disclose issuance totals. CoinDesk reported that REC raised Rs. 500 crore, Larsen & Toubro raised Rs. 500 crore and IIFL Finance raised Rs. 25 crore through the system, a combined Rs. 1,025 crore. The report also said the bonds retained conventional interest rates, maturity dates and investor rights. Those figures and issuer names are independently reported context, not information confirmed in SEBI's release or FAQ.
SEBI has not announced a public rollout date, a retail start date, a new exchange, an open-network model, token-holder rights beyond the underlying bond's existing rights, or named private-sector technology partners. The regulator's disclosed plan instead keeps the pilot within depository, exchange, CBDC and sandbox arrangements while it tests the system's operational and regulatory limits.