Loading article...

A technical guide to careers in Web3 insurance and risk management, covering smart contract underwriting, parametric claims execution, actuarial risk modeling, and protocol security evaluation.
Decentralized Finance (DeFi) protocols manage tens of billions of dollars in Total Value Locked (TVL), yet the permissionless nature of smart contracts introduces unique operational vectors: reentrancy exploits, oracle price manipulation, flash loan attacks, and economic de-pegging events. Over the past decade, billions of dollars have been lost due to protocol vulnerabilities and unhedged market risks.
As institutional capital, fintech corporations, and mainstream asset managers enter the Web3 ecosystem, robust insurance coverage and quantitative risk management have become mandatory prerequisites.
This technical career guide explores the emerging discipline of Web3 Insurance and Risk Management, examining smart contract underwriting, parametric claims execution, actuarial loss modeling, key protocols, and career pathways for security researchers, actuaries, and quantitative analysts.
Risk management in Web3 differs fundamentally from traditional property and casualty (P&C) or financial line insurance. Web3 risk underwriters evaluate two interconnected risk domains:
                      WEB3 RISK EVALUATION FRAMEWORK

 ┌────────────────────────────────────────────────────────────────────────┐
 │ 2. ECONOMIC & SYSTEMIC RISKS (Oracle Spikes, Flash Loans, De-pegging)   │
 ├────────────────────────────────────────────────────────────────────────┤
 │ 1. TECHNICAL SECURITY RISKS  (Reentrancy, Integer Overflow, Access Control)│
 └────────────────────────────────────────────────────────────────────────┘
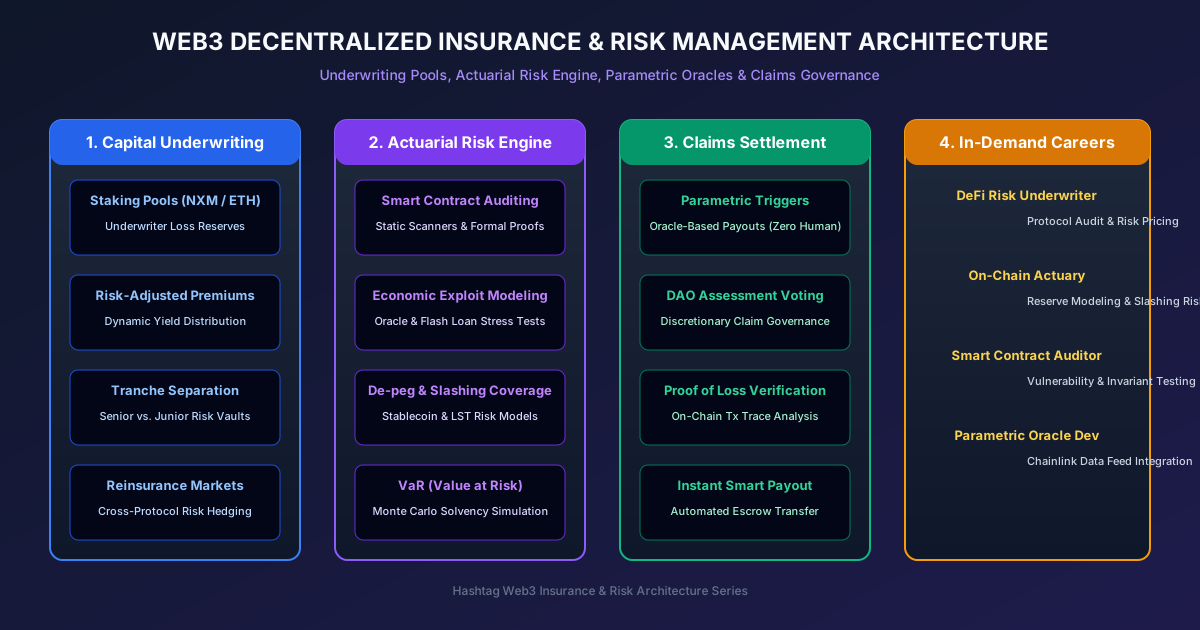
Decentralized insurance protocols (such as Nexus Mutual, InsurAce, and Unslashed) replace traditional insurance companies with capital pools governed by smart contracts and token-weighted risk assessors.
                  DECENTRALIZED MUTUAL INSURANCE FLOW

 ┌─────────────────┐       ┌─────────────────┐       ┌─────────────────┐
 │ Policy Buyer    │ ────► │ Underwriting    │ ────► │ Capital Pool    │
 │ (Pays Premium)  │       │ Smart Contract  │       │ (Staker Capital)│
 └─────────────────┘       └─────────────────┘       └────────┬────────┘
                                                              │
                                                              ▼
 ┌─────────────────┐       ┌─────────────────┐       ┌─────────────────┐
 │ Claims Payment  │ ◄──── │ Claims Assessor │ ◄──── │ Exploit Event   │
 │ (Instant Payout)│       │ Voting / Oracle │       │ Trigger         │
 └─────────────────┘       └─────────────────┘       └─────────────────┘
As the market for Web3 risk coverage expands, specialized roles are emerging at the intersection of cybersecurity, actuarial science, and quantitative finance.
                           CAREER SPECIALIZATION ROADMAP

 [Traditional Actuary / Security Researcher / Quant Analyst]
                             │
                             ├───────────────────────┬───────────────────────┐
                             ▼                       ▼                       ▼
                  [Smart Contract Underwriter]  [On-Chain Actuary]     [DeFi Risk Manager]
                  - Audit Log Analysis          - Loss Reserve Modeling - Oracle Stress Testing
                  - Vulnerability Scoring        - Slashing Risk Math    - Portfolio VaR Models
Several key protocols and risk management firms define the industry standard for on-chain risk underwriting:
| Protocol / Firm | Category | Core Mechanics & Products | Primary Focus |
|---|---|---|---|
| Nexus Mutual | Discretionary Mutual | Staker-backed capital pools, NXM token governance | Smart contract cover, ETH slashing cover, custodial risk |
| InsurAce.io | Multi-Chain Insurance | Portfolio-based coverage, zero-KYC options | DEX cross-chain portfolio insurance, stablecoin de-peg cover |
| Gauntlet Networks | Quantitative Risk Mgmt | Financial simulation engines, automated parameter tuning | Aave/Compound interest rate & collateral LTV optimization |
| Chaos Labs | Security & Risk Simulation | Agent-based economic stress testing, oracle risk monitors | Real-time DeFi protocol risk parameter monitoring |
| Sherlock | Audit & Insurance Hybrid | Audit contest platform backed by $10M+ exploit coverage | Integrated smart contract security auditing with protocol insurance |
To maintain financial stability, decentralized insurance protocols adopt Solvency Capital Requirements modeled after Solvency II regulatory frameworks in traditional insurance.
                    RISK TRANCHING & CAPITAL RESERVES STACK

 ┌────────────────────────────────────────────────────────────────────────┐
 │ SENIOR TRANCHE VAULTS    (Low Yield, High Safety, First-Out Coverage)  │
 ├────────────────────────────────────────────────────────────────────────┤
 │ JUNIOR TRANCHE VAULTS    (High Yield, First-Loss Absorption Capital)   │
 ├────────────────────────────────────────────────────────────────────────┤
 │ EMERGENCY REINSURANCE    (Cross-Protocol Risk Hedges, ETH/USDC Backing)│
 └────────────────────────────────────────────────────────────────────────┘
Parametric insurance eliminates manual claim assessments by linking payouts directly to cryptographic oracles and verifiable on-chain metrics.
                 PARAMETRIC AUTOMATED CLAIMS PIPELINE

 ┌─────────────────┐       ┌─────────────────┐       ┌─────────────────┐
 │ Chainlink       │ ────► │ Custom Oracle   │ ────► │ Parametric      │
 │ Data Feeds      │       │ Script          │       │ Smart Contract  │
 └─────────────────┘       └─────────────────┘       └────────┬────────┘
                                                              │
                                                              ▼
 ┌─────────────────┐       ┌─────────────────┐       ┌─────────────────┐
 │ Instant Claim   │ ◄──── │ Verify Breach   │ ◄──── │ Threshold Check │
 │ Transfer        │       │ Condition       │       │ (`price < $0.90`)│
 └─────────────────┘       └─────────────────┘       └─────────────────┘
claim() function on the insurance contract, instantly transferring funds to policyholders without human intervention.Below is a complete Python script demonstrating how an actuarial risk engine calculates Value at Risk (VaR) and sets risk-adjusted insurance premiums for a DeFi liquidity pool:
import numpy as np

class DefiRiskEngine:
    """Calculates risk-adjusted insurance premiums using Monte Carlo simulation."""
    def __init__(self, historical_audit_score, tvl_usd, complexity_factor):
        self.audit_score = historical_audit_score # 0 to 100
        self.tvl = tvl_usd
        self.complexity = complexity_factor # 1.0 (Simple) to 3.0 (Complex)

    def calculate_base_probability_of_failure(self):
        # Base annual exploit probability derived from audit quality & complexity
        base_prob = (100 - self.audit_score) * 0.0005 * self.complexity
        return max(0.005, min(base_prob, 0.25)) # Clamp between 0.5% and 25%

    def run_monte_carlo_loss_simulation(self, iterations=10000):
        annual_prob = self.calculate_base_probability_of_failure()
        simulated_losses = []

        for _ in range(iterations):
            # Binomial trial: Does an exploit occur this year?
            exploit_occurred = np.random.rand() < annual_prob
            if exploit_occurred:
                # Loss severity distribution (Beta distribution skewed toward 40-80% pool drain)
                severity = np.random.beta(a=2, b=1.5)
                loss_amount = self.tvl * severity
            else:
                loss_amount = 0.0
            simulated_losses.append(loss_amount)

        var_95 = np.percentile(simulated_losses, 95)
        expected_annual_loss = np.mean(simulated_losses)
        return expected_annual_loss, var_95

    def calculate_annual_premium(self, profit_margin=0.20):
        expected_loss, var_95 = self.run_monte_carlo_loss_simulation()
        pure_premium = expected_loss
        risk_capital_charge = (var_95 - expected_loss) * 0.05
        gross_premium = (pure_premium + risk_capital_charge) * (1 + profit_margin)
        premium_rate_pct = (gross_premium / self.tvl) * 100
        return gross_premium, premium_rate_pct

# Execution Example
risk_engine = DefiRiskEngine(historical_audit_score=85, tvl_usd=50000000, complexity_factor=1.8)
premium_usd, rate_pct = risk_engine.calculate_annual_premium()

print("=== DEFI PROTOCOL RISK & PREMIUM ASSESSMENT ===")
print(f"Target Protocol TVL: ${risk_engine.tvl:,.2f}")
print(f"Calculated Annual Exploit Probability: {risk_engine.calculate_base_probability_of_failure()*100:.2f}%")
print(f"Annual Policy Premium (USD): ${premium_usd:,.2f}")
print(f"Risk Premium Rate: {rate_pct:.2f}% per annum")
Software engineers, actuaries, and risk managers looking to transition into Web3 risk roles should execute the following strategy:
Candidates interviewing for Web3 risk and underwriting positions are evaluated on scenario-based technical questions.
Question: "A new liquid staking protocol requests $50 Million in smart contract insurance cover. How do you structure the underwriting risk evaluation before approving the policy?"
Answer:
Question: "An oracle price manipulation attack causes a lending protocol to issue $5 Million in bad debt. Does a standard 'Smart Contract Malfunction' policy cover this loss?"
Answer:
Question: "In discretionary mutuals like Nexus Mutual, how do you prevent token holders from voting to reject valid claims to preserve their own capital reserves?"
Answer:
Question: "How do actuaries price insurance coverage for automated market maker (AMM) liquidity providers suffering impermanent loss during volatile token swings?"
Answer:
$$\text{IL}(r) = \frac{2 \sqrt{r}}{1 + r} - 1$$
To prevent single smart contract exploits from causing systemic insolvency, the Web3 insurance ecosystem is adopting traditional reinsurance and collateral securitization frameworks:
As institutional asset managers allocate capital to Web3 protocols, regulatory bodies across global jurisdictions are establishing risk compliance frameworks:
Question: "During extreme network congestion, Ethereum gas prices spike to 500 gwei, delaying liquidator transactions. How does a risk manager model liquidation failure risk under high gas volatility?"
Answer:
Modern Web3 risk management platforms (such as Chaos Labs and Gauntlet) deploy agent-based simulation engines to stress-test protocol solvency under simulated crisis conditions:
Web3 insurance and risk management represent a critical pillar for the institutional scaling of decentralized finance. By combining smart contract security audits, quantitative economic simulations, and actuarial reserve modeling, risk professionals ensure that decentralized protocols remain solvent even during severe market stress.
Mastering these risk engineering methodologies equips software developers, actuaries, and financial analysts to lead high-paying careers shaping the future of Web3 risk management.
Explore more guides and career playbooks