Loading article...

The Federal Reserve asked for 60 days of public comment on two proposals that would set reserve backing, capital standards and a bank application process for stablecoin issuers under the GENIUS Act.
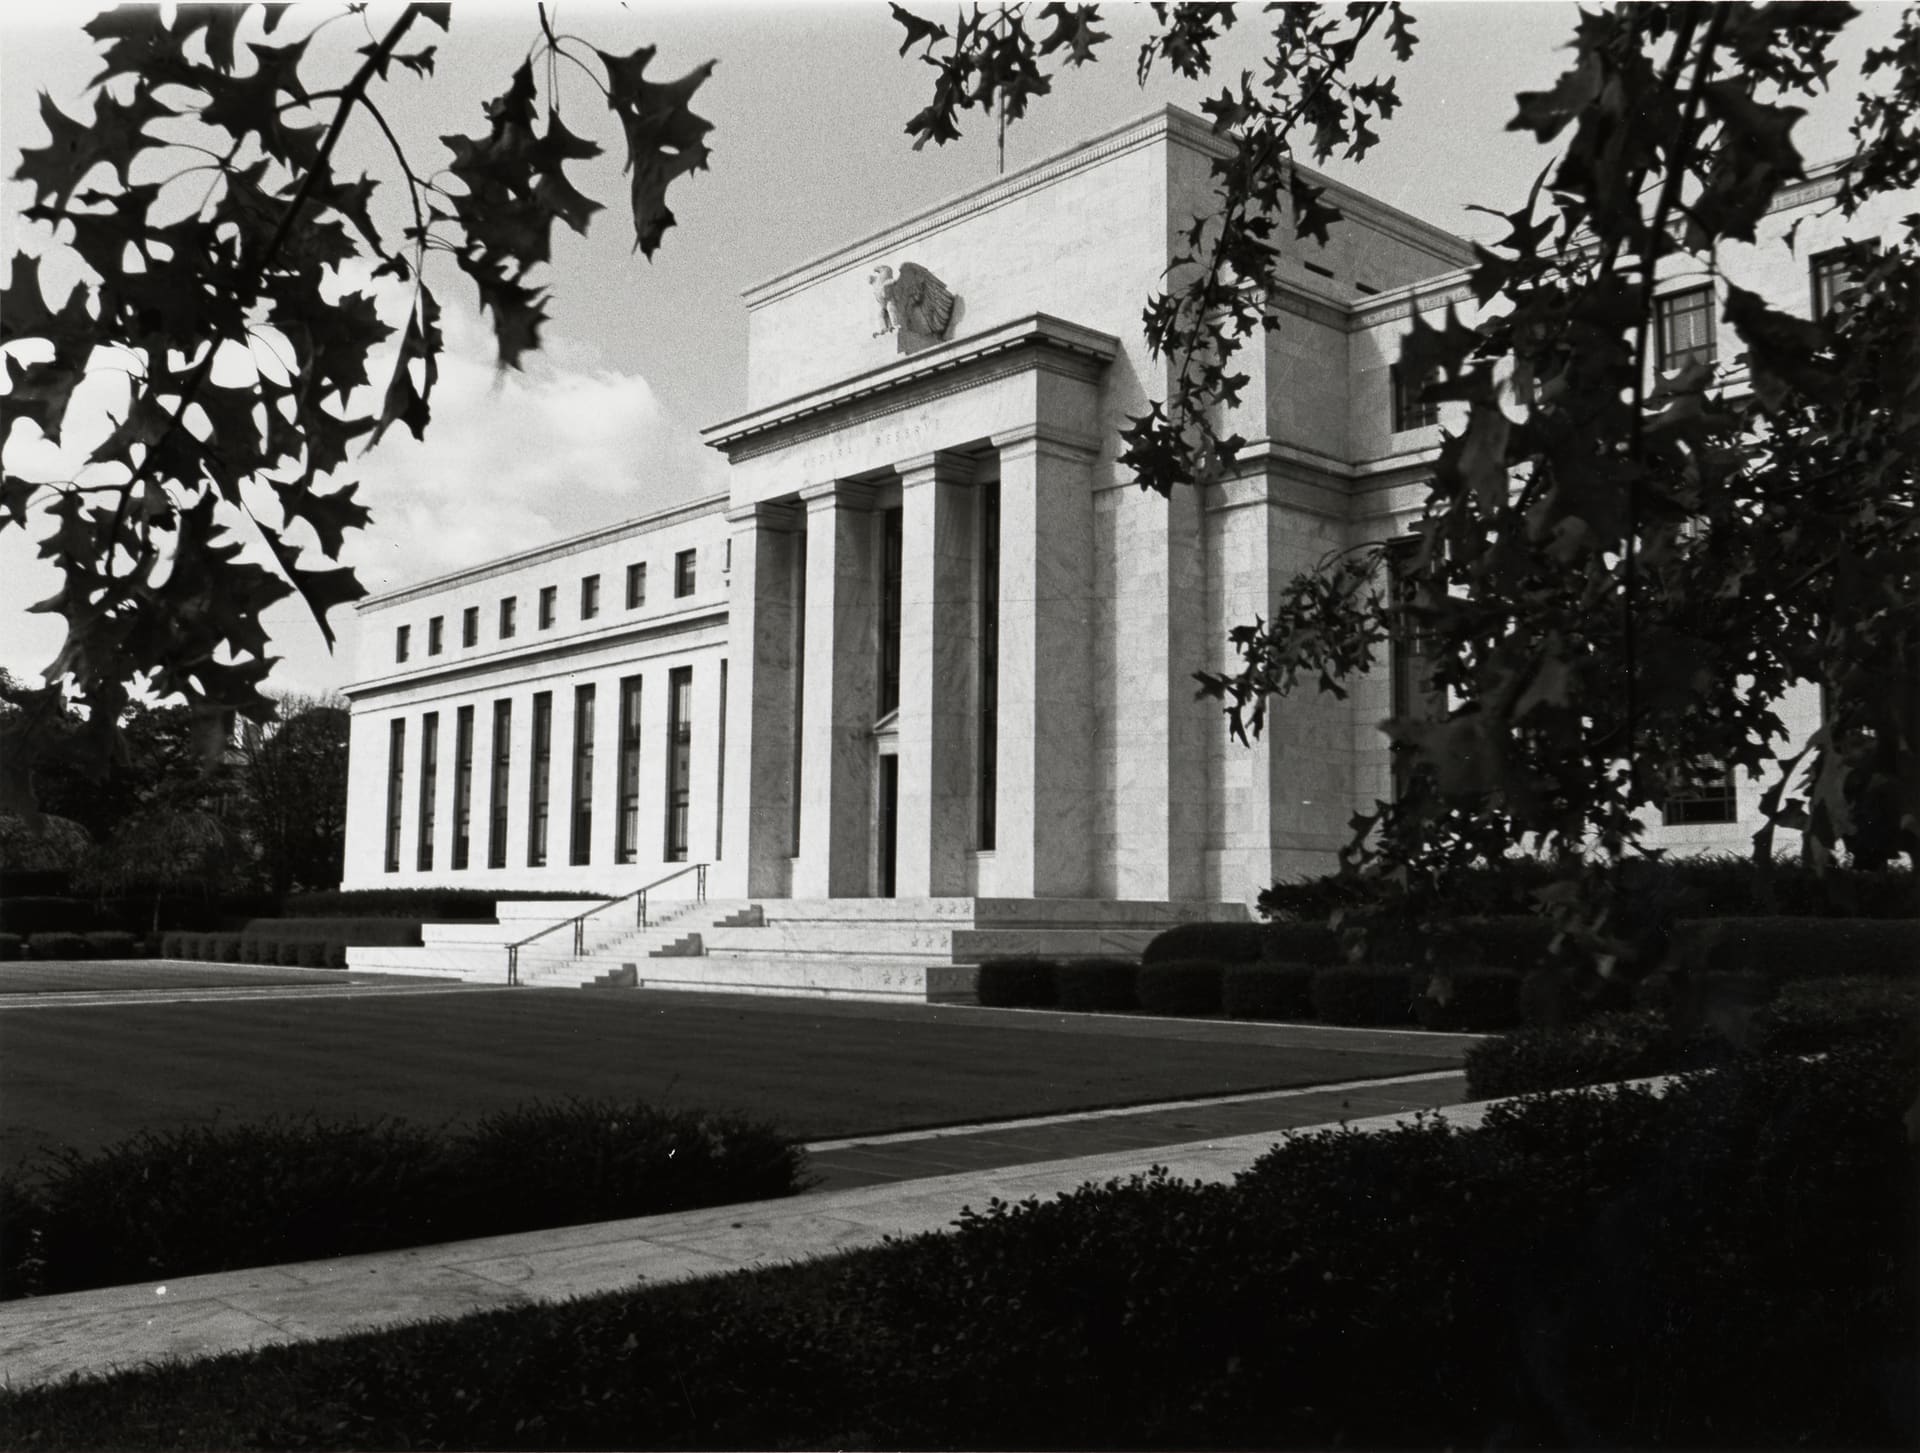
The Marriner S. Eccles Federal Reserve Board Building in Washington. Photo: Federalreserve via Wikimedia Commons (Public domain). Source
The Federal Reserve asked for public comment on September 24 on two proposals that would set the regulatory framework for the stablecoin issuers it supervises under the GENIUS Act. The announcement opens 60-day comment periods that run from publication in the Federal Register.
The first proposal covers how Board-supervised payment stablecoin issuers must back their tokens and capitalize themselves. Issuers would have to fully back outstanding stablecoins with specified reserve assets such as short-term Treasury bills and other high-quality liquid assets, the notice states. It would also impose standardized capital requirements tied to credit and operational risk, plus risk management standards required by the law.
That same proposal addresses firms that hold the reserve assets for issuers. Board-supervised firms that safekeep backing assets would face dedicated rules under the draft, and the Fed would clarify which stablecoin and related activities its supervised banks may conduct. The text does not set final compliance dates, since the drafts must still go through comment and revision.
The second proposal sets up the door banks would walk through to issue stablecoins. A Board-supervised bank seeking approval for a subsidiary to issue payment stablecoins would file a tailored application with a business plan, financial information and policies, procedures and related documents, according to the release. The draft also creates procedures for appeals, hearings and final determinations on those applications.
One closely watched section governs stablecoin rewards. CoinDesk described the Fed language as presuming that certain arrangements involving third parties count as prohibited payments of interest or yield. That treatment tracks the policy the Office of the Comptroller of the Currency already sketched, and the report said the practical effect could leave room only for narrow programs structured like credit-card incentives.
The rewards question carried weight beyond this rulemaking. Efforts to rewrite the yield rules inside the Digital Asset Market Clarity Act failed, so the GENIUS Act remains the controlling law on what issuers and platforms can pay holders. Coinbase was among the companies with a direct stake in where that line lands, though the proposals do not name any company.
The drafts arrive past the statute's original schedule. The GENIUS Act, signed last year, directed banking regulators and the Treasury Department to write implementing rules by July 2026, a deadline the agencies missed. The law creates a federal framework that requires full backing in dollars or similarly liquid assets alongside annual audits, The Block wrote in its account of the September 24 action. Its substantive requirements take effect in January 2027.
Other regulators have moved their own pieces in recent months. The Treasury Department proposed definitions of who issues a U.S. stablecoin and who must follow the law in August. The Federal Deposit Insurance Corp. opened the agency process with a December proposal, and several agencies jointly proposed customer identification rules for issuers in June that resemble bank requirements. CoinDesk placed the Fed drafts as the latest step in that sequence rather than the finish.
Fed Governor Michael Barr said he backed the September 24 proposals while flagging a money-laundering concern. He objected to language that would bar Board action on an anti-money-laundering shortfall unless the problem is deemed significant or systemic. The Block quoted his warning that the standard could have unknown effects on the Board's ability to demand compliant programs, echoing concerns he raised about a July proposal.
Barr separately tied the reserve rules to redemption under stress. "Stablecoins will only be stable if they can be reliably and promptly redeemed at par in a range of conditions," he said in a statement linked from the release, pointing to pressure on even liquid government debt during market strain and to stress at an issuer or its affiliates.
Proposed rules now enter the standard federal cycle. The Fed will collect comment for 60 days after Federal Register publication, then revise the drafts before publishing final versions, a process that often takes months. The Board memos and draft Federal Register notices are attached to the September 24 release for commenters to address.