
What Is a Fair Launch in Cryptocurrency
An empirical technical thesis on cryptocurrency fair launches and token distribution mechanisms, examining Proof-of-Work origins, Balancer LBPs, bonding curves, Sybil resistance, and securities regulatory boundaries.
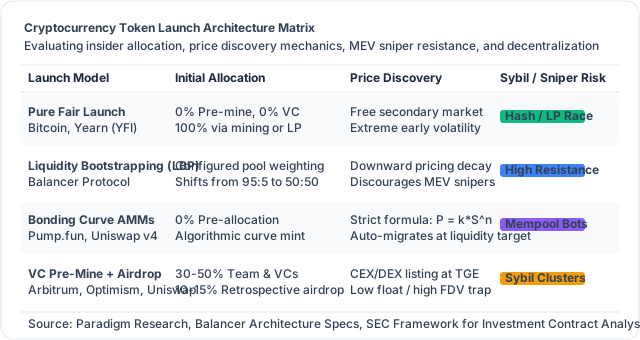
In decentralized systems, the mechanism by which a digital asset is initially minted, priced, and distributed across network participants determines its long-term decentralization, economic stability, and regulatory classification.
A fair launch represents a token distribution architecture in which a cryptocurrency is released to the public with zero pre-mine, zero preferential private allocations to venture capital funds or insiders, and completely equal access to acquisition from the genesis block onward.
While the fair launch was the foundational distribution model of early cypherpunk protocols like Bitcoin, the professionalization of Web3 development introduced complex alternative architectures: venture-backed pre-mines, retrospective community airdrops, Balancer Liquidity Bootstrapping Pools (LBPs), and algorithmic bonding curves.
Understanding the technical, economic, and legal realities of these competing models is essential for protocol engineers, tokenomics architects, and securities compliance specialists.
Historical Genesis: The Classical Cypherpunk Fair Launch
The concept of a fair launch originated with Satoshi Nakamoto in the launch of Bitcoin in January 2009, as documented in the Bitcoin Whitepaper.
The characteristics of the canonical cypherpunk launch set the benchmark for decentralized fairness:
- Public Advance Notice: The release was announced openly on the Cryptography Mailing List, ensuring that all participants received equal advance information.
- Zero Pre-Mine: Not a single satoshi was minted or allocated to Satoshi Nakamoto or early developers prior to the publicly broadcast genesis block.
- Open Hardware Participation: Every individual possessing a standard consumer central processing unit (CPU) could run node software and mine blocks under identical cryptographic Proof of Work rules.
- Thermodynamic Economic Cost: Minting new tokens required real expenditures of computational energy, establishing an unforgeable baseline of production cost.
Early alternative blockchains such as Litecoin and Monero preserved this model, demonstrating that grassroots Proof of Work issuance could bootstrap globally distributed networks without central corporate coordination.
The Evolution of Token Distribution Archetypes
As decentralized computing evolved from simple value transfer ledgers into complex smart contract protocols deployed on Ethereum, Arbitrum, and Base, the capital required to hire cryptography engineers, fund smart contract security audits with firms like Trail of Bits and OpenZeppelin, and provide initial liquidity necessitated new funding paradigms.
1. Initial Coin Offerings (ICOs) and the 2017 Bubble
In 2017, protocols pioneered Initial Coin Offerings (ICOs), selling pre-mined ERC-20 tokens directly to the global public in exchange for ETH or BTC:
- Structural Flaw: Most ICO projects collected hundreds of millions of dollars before writing a single line of production code, creating immense moral hazard.
- Regulatory Backlash: The U.S. Securities and Exchange Commission (SEC) issued the landmark DAO Report of Investigation (Release No. 81207), establishing that public token sales without registered prospectuses violated federal securities laws under SEC v. W.J. Howey Co. (328 U.S. 293). This triggered aggressive enforcement actions that effectively terminated unrestricted public ICOs in Western jurisdictions.
2. The DeFi Fair Launch: Andre Cronje and Yearn Finance (YFI)
In July 2020, during the height of the decentralized finance boom, Andre Cronje launched Yearn Finance and its governance token, YFI:
- Radical Cypherpunk Distribution: Cronje announced that YFI had "zero financial value, 0 pre-mine, 0 sale, and 0 team allocation."
- 100% Liquidity Mining: The entire supply of 30,000 YFI was distributed programmatically over a seven-day window to users who supplied liquidity into Curve Finance yCRV pools.
- Outcome: YFI became one of the most celebrated fair launches in Web3 history, surging in value to surpass the price of Bitcoin and demonstrating that fair liquidity distribution could build intense community loyalty.
However, YFI also exposed a major structural flaw of DeFi fair launches: capital concentration. Because tokens were distributed in strict proportion to capital supplied into liquidity pools, wealthy crypto funds and "whales" deployed tens of millions of dollars, harvesting the overwhelming majority of the token supply and pricing out grassroots retail participants.
3. Liquidity Bootstrapping Pools (LBPs): Dynamic Reverse Auctions
To prevent wealthy participants and automated MEV sniping bots from monopolizing token launches on standard automated market makers, developers created Liquidity Bootstrapping Pools (LBPs), pioneered by Balancer Protocol.
An LBP functions as a continuous downward-decaying Dutch auction:
- The pool is initialized with a high project token weight (such as 95% project token and 5% USDC), creating an artificially high starting price.
- Over a predefined multi-day window (typically 48 to 72 hours), the pool weights gradually rebalance to 50% project token and 50% USDC.
- This continuous mathematical downward pricing pressure disincentivizes automated MEV bots from frontrunning the launch, because any bot purchasing tokens at the genesis block pays the absolute peak price. Legitimate community members wait for the price to decline to a fair valuation before executing trades.
4. Algorithmic Bonding Curves: Pump.fun and Uniswap v4 Hooks
The newest evolution in fair token launches is the algorithmic bonding curve, popularized by platforms like Pump.fun on Solana and decentralized implementations using custom hooks on Uniswap v4:
$$ ext{Price} = k \cdot S^n$$
Where $S$ represents the circulating supply and $k, n$ are mathematical curve parameters.
Bonding curves completely eliminate private investor discounts and manual liquidity seeding:
- Every buyer, from the token creator to the general public, purchases tokens against the exact same immutable mathematical curve.
- Collateral deposited by buyers accumulates in a non-custodial smart contract vault.
- Once the bonding curve target is reached, the protocol automatically transfers accumulated liquidity into an automated market maker pool and burns the LP tokens, ensuring that liquidity can never be pulled or stolen by creators.
The Sybil Threat: Why Modern Launches Struggle with Fairness
In the era of anonymous cryptographic addresses, the greatest obstacle to executing a fair token launch is the Sybil attack, formalized by John R. Douceur in 2002.
When a protocol announces a community airdrop or fair distribution based on user activity (such as interacting with smart contracts or bridging assets):
- Industrial Sybil syndicates deploy automated scripts, operating thousands of distinct, funded wallets to simulate organic activity.
- Data research from Dune Analytics and Nansen reveals that during major Layer 2 airdrops (including Arbitrum, Optimism, and Starknet), Sybil clusters extracted tens of millions of dollars in tokens, heavily diluting genuine community contributors.
Sybil Defense Infrastructures
To protect token distributions from automated exploitation, modern protocols integrate decentralized identity and anti-Sybil infrastructures:
- Gitcoin Passport: Aggregates verifiable credentials (such as GitHub commits, ENS domains, Google accounts, and on-chain tenure) into a cryptographic anti-Sybil score.
- Zero-Knowledge Proof of Humanity: Protocols utilizing Worldcoin or Proof of Humanity verify uniqueness through zero-knowledge biometric or web-of-trust proofs without revealing personal identity.
- On-Chain Graph Clustering: Analytics algorithms track wallet transaction graphs, identifying and blacklisting clusters that share common funding sources or execute identical transaction timestamps.
Legal and Regulatory Architecture: The SEC Howey Framework
The legal distinction between a fair launch and an institutional token sale is one of the most critical topics in contemporary blockchain jurisprudence.
In the United States, the SEC evaluates digital assets under the four-prong test established in SEC v. W.J. Howey Co.:
Why True Fair Launches Possess Superior Regulatory Defenses
In official guidance and speeches (such as former SEC Director William Hinman's 2018 address on decentralization), regulators recognized that when a network becomes "sufficiently decentralized," the fourth prong of the Howey Test breaks down:
- In a pure fair launch like Bitcoin, purchasers do not rely on the managerial efforts of a centralized promoter or corporate executive team. There is no issuer, no common enterprise, and no enterprise balance sheet.
- Consequently, Bitcoin was formally classified by both the SEC and the Commodity Futures Trading Commission (CFTC) as a non-security commodity.
- Conversely, protocols that raise capital through private Simple Agreements for Future Tokens (SAFTs) with venture capital firms, conduct pre-mines, and retain large insider allocations remain vulnerable to regulatory enforcement, fines, and trading restrictions.
Comparative Matrix: Evaluating Modern Launch Architectures
For protocol engineering teams evaluating how to structure a token generation event, this matrix synthesizes the structural trade-offs:
- Select a Fair Launch (or Bonding Curve AMM) if your protocol is community-first, does not require millions in upfront enterprise development capital, and prioritizes regulatory resilience and broad decentralization.
- Select a Balancer Liquidity Bootstrapping Pool (LBP) if your project requires public capital raising but wants to eliminate MEV frontrunning and achieve smooth price discovery.
- Select a VC Pre-Mine with Airdrop if your protocol requires immense multi-year research and development expenditures (such as zero-knowledge provers or core Layer 1 consensus clients) where venture capital funding is indispensable prior to launch.
By mastering the mechanics of liquidity decay curves, bonding algorithms, and anti-Sybil verification, decentralized protocol engineers can deploy robust token launches that honor cypherpunk ideals while surviving the realities of modern algorithmic markets.
Further reading
- Bitcoin: A Peer-to-Peer Electronic Cash System Whitepaper
- U.S. Securities and Exchange Commission (SEC) EDGAR Database
- SEC Framework for 'Investment Contract' Analysis of Digital Assets
- SEC Report of Investigation: The DAO (Release No. 81207)
- Commodity Futures Trading Commission (CFTC) Digital Asset Resources
- Balancer Protocol Liquidity Bootstrapping Pool Specification