Loading article...

A comprehensive technical guide to Liquidity Bootstrapping Pools, dynamic weight decay mathematics, anti-bot price discovery, and capital-efficient token launches.
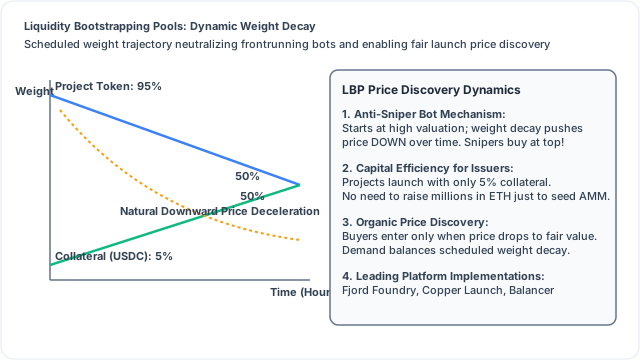
Decentralized token launches have historically struggled with adverse selection, capital constraints, and predatory bot activity. Early token distribution models, such as Initial Coin Offerings (ICOs) and Initial DEX Offerings (IDOs) documented in Ethereum Developer Documentation and early bonding curve protocols like Bancor Protocol on constant product automated market makers, suffered from structural flaws. When a project launched a token on a standard fifty-fifty automated market maker, the first blocks of trading were routinely captured by automated sniper bots, causing catastrophic price spikes followed by retail dumping.
The Liquidity Bootstrapping Pool (LBP), invented by Balancer and built upon the open-source Balancer Core Contracts documented at Balancer Docs, introduced an elegant algorithmic mechanism designed to achieve decentralized, fair, and bot-resistant price discovery.
By utilizing dynamic, time-decaying pool weights, an LBP continuously applies downward pressure on token prices throughout the sale event. This dynamic turns automated market making into a continuous Dutch auction (expanding on Dutch auction primitives like Gnosis DutchX and auction research from Paradigm on Batch Auctions and VRGDAs), enabling nascent decentralized organizations to raise capital and distribute tokens without prohibitive upfront collateral or vulnerability to front-running bots.
To appreciate the architectural necessity of Liquidity Bootstrapping Pools, one must examine the mechanics of traditional token launches executed on protocols like Uniswap v2.
In a conventional fifty-fifty automated market maker formalized in the Uniswap v2 Whitepaper (and contrasted with concentrated models in Uniswap v3, pegged stableswap models in Curve Finance, and volatile multi-token models in Curve Crypto Pools), the pool requires project founders to deposit equal dollar values of the project token and a quote asset, typically USDC, DAI, or WETH:
$$x \cdot y = k$$
This requirement creates two severe structural vulnerabilities:
Liquidity Bootstrapping Pools solve these structural issues by generalizing the Constant Mean Market Maker formula utilizing fixed-point computational libraries including LogExpMath.sol, FixedPoint.sol, and PRBMath, compliant with the Solidity Language Specification and Ethereum Yellow Paper, with gas costs optimized via EIP-1153 Transient Storage originally developed by Balancer:
$$V = \prod_{i=1}^{n} B_i^{w_i(t)}$$
In this invariant, $B_i$ represents the reserve balance of token $i$, while $w_i(t)$ represents the normalized weight of token $i$ as a continuous function of block time $t$.
An LBP typically contains two tokens: the newly issued project token ($p$) and a stable reserve collateral token ($c$), such as USDC or WETH, conforming to the ERC-20 Standard and ERC-2612 Permit. The pool parameters specify:
At any timestamp $t$ where $t_{start} \le t \le t_{end}$, the normalized weights are updated linearly by the pool controller smart contract:
$$w_p(t) = w_p(t_{start}) + \frac{t - t_{start}}{t_{end} - t_{start}} \cdot \left( w_p(t_{end}) - w_p(t_{start}) \right)$$
$$w_c(t) = 1 - w_p(t)$$
The spot price $P(t)$ of the project token denominated in collateral units at timestamp $t$ is calculated by dividing reserve balances adjusted for dynamic weights:
$$P(t) = \frac{B_c(t) / w_c(t)}{B_p(t) / w_p(t)} = \frac{B_c(t) \cdot w_p(t)}{B_p(t) \cdot w_c(t)}$$
Examine what occurs to the spot price if absolutely no trading occurs ($B_c$ and $B_p$ remain constant):
$$\text{As } t \to t_{end}, \quad w_p(t) \text{ decreases from } 0.95 \to 0.50, \quad \text{and } w_c(t) \text{ increases from } 0.05 \to 0.50$$
Substituting these values into the spot price equation reveals a dramatic price trajectory:
$$P(t_{start}) = \frac{B_c \cdot 0.95}{B_p \cdot 0.05} = 19 \cdot \frac{B_c}{B_p}$$
$$P(t_{end}) = \frac{B_c \cdot 0.50}{B_p \cdot 0.50} = 1 \cdot \frac{B_c}{B_p}$$
In the complete absence of buy transactions, the programmatic shift in weights causes the token price to drop by:
$$\frac{19 - 1}{19} = 94.74%$$
This programmatic price decline exerts continuous, predictable downward pressure on the token price throughout the duration of the bootstrapping event.
The real-time market price during a Liquidity Bootstrapping Pool is governed by the continuous interplay of two opposing market forces:
If market demand exceeds the rate of downward weight decay, the token price rises. If market demand is lower than the weight decay, the price continues to drift downward.
When the market price reaches a level that investors perceive as fair value, steady buying activity balances the weight decay, causing the price to stabilize sideways. This process enables genuine market-clearing price discovery without requiring an external price feed or oracle.
The core innovation of the Liquidity Bootstrapping Pool is its game-theoretic elimination of the sniper bot advantage.
In a standard fixed-weight pool, the optimal strategy for a profit-maximizing bot is to purchase tokens in the earliest possible block. In an LBP, purchasing tokens at the initial block guarantees that the buyer pays the absolute highest theoretical valuation of the sale.
If a sniper bot buys tokens in block 0:
Consequently, rational MEV searchers and automated bots have no economic incentive to snipe the initial liquidity deposit.
Human participants and decentralized autonomous organizations face a classic game-theoretic optimization problem:
This dynamic aligns participant incentives toward honesty. Investors place buy orders when the token reaches a valuation they personally consider fair, rather than racing against automated bots in high-gas transaction wars.
Liquidity Bootstrapping Pools reduce the upfront capital required to conduct a public token distribution by orders of magnitude.
Consider a comparison between launching a token via a 50/50 Uniswap pool versus a 95/5 Balancer LBP, assuming the founding team wishes to initialize trading at a $20 million implied valuation:
In the 50/50 pool, the founding team must supply $2,000,000 in liquid stablecoins to pair with their tokens. In the 95/5 LBP, the team achieves the exact same initial unit price of $0.20 with only $105,263 in collateral.
This 95% reduction in upfront capital allows open-source developers, research collectives, and decentralized autonomous organizations to launch functional secondary market liquidity without seeking external bridge financing or private token sales.
While Balancer provides the core mathematical smart contracts and the centralized Vault.sol infrastructure, user-facing LBP distribution has largely transitioned to specialized launch platforms:
Fjord Foundry built a permissionless protocol layer on top of Balancer, providing:
An LBP is designed as a temporary price discovery mechanism, typically operating for 48 to 72 hours. Once the scheduled weight transition completes, the bootstrapping phase ends, and the protocol must transition its liquidity into a permanent market structure.
Modern decentralized protocols utilize the proceeds generated during an LBP to seed permanent Protocol-Owned Liquidity rather than distributing capital to team wallets:
To observe how dynamic weight decay balances participant buy pressure in practice, consider a numerical simulation of an emerging decentralized protocol conducting a 72-hour Liquidity Bootstrapping Pool.
The founding team deploys an LBP with the following on-chain parameters:
$$P_{spot}(0) = \frac{100{,}000 / 0.05}{10{,}000{,}000 / 0.95} = \frac{2{,}000{,}000}{10{,}526{,}315.79} = $0.190$$
This establishes an initial fully diluted valuation of $19.0 million for a 100-million token total supply, requiring only $100,000 in liquid capital from the project treasury.
Over the 72-hour duration, the smart contract linearly interpolates weights across every block. The table below traces pool state transitions across 12-hour intervals under realistic trading scenarios:
In this simulation, the programmatic weight decay caused the price to drop from $0.190 to $0.060 in the first 24 hours. Because sniper bots faced severe immediate losses by purchasing early, retail investors and decentralized autonomous organizations waited until the price fell into a range they considered reasonable ($0.060 to $0.070).
As buying volume entered the pool, the purchasing rate counteracted the remaining weight decay, allowing the market to clear at $0.098.
At the conclusion of the event:
Creating a custom Liquidity Bootstrapping Pool requires interacting with the Balancer v2 Factory contracts and configuring a dynamic weight controller.
Tested using the Foundry Framework and Hardhat, analyzed with Slither, Echidna, and Halmos, and adhering to audited security standards from OpenZeppelin Contracts, Trail of Bits, Certora, and ConsenSys Diligence, the following complete Solidity contract demonstrates how a project team configures and deploys an automated weight update schedule for an LBP, compatible with Ethers.js, Viem, Wagmi, RainbowKit, MetaMask SDK, and WalletConnect, verifiable on Etherscan:
// SPDX-License-Identifier: MIT
pragma solidity ^0.8.24;

interface IGradualWeightUpdatePool {
    function updateWeightsGradually(
        uint256 startTime,
        uint256 endTime,
        uint256[] memory endWeights
    ) external;

    function setSwapEnabled(bool swapEnabled) external;

    function getNormalizedWeights() external view returns (uint256[] memory);
}

/// @notice Secure management contract for scheduling dynamic LBP weight transitions
contract LBPController {
    address public immutable owner;
    IGradualWeightUpdatePool public immutable lbpPool;

    error OnlyOwnerAllowed();
    error InvalidTimeParameters();
    error InvalidWeightConfiguration();

    event WeightsGraduationScheduled(uint256 startTime, uint256 endTime, uint256[] targetWeights);
    event SwappingStateToggled(bool enabled);

    modifier onlyOwner() {
        if (msg.sender != owner) revert OnlyOwnerAllowed();
        _;
    }

    constructor(address _poolAddress) {
        owner = msg.sender;
        lbpPool = IGradualWeightUpdatePool(_poolAddress);
    }

// @notice Initiates dynamic weight decay over a fixed duration
// @param durationInSeconds Duration of the bootstrapping event (e.g. 259200 for 72 hours)
// @param endWeightProject Target final weight for project token in 18-decimal fixed point (e.g. 0.5e18)
// @param endWeightCollateral Target final weight for collateral token (e.g. 0.5e18)
    function scheduleWeightDecay(
        uint256 durationInSeconds,
        uint256 endWeightProject,
        uint256 endWeightCollateral
    ) external onlyOwner {
        if (durationInSeconds < 3600) revert InvalidTimeParameters();
        if (endWeightProject + endWeightCollateral != 1e18) revert InvalidWeightConfiguration();

        uint256 startTime = block.timestamp;
        uint256 endTime = startTime + durationInSeconds;

        uint256[] memory endWeights = new uint256[](2);
        endWeights[0] = endWeightProject;
        endWeights[1] = endWeightCollateral;

/ Schedule programmatic linear interpolation in pool contract
        lbpPool.updateWeightsGradually(startTime, endTime, endWeights);

/ Enable public swapping on the AMM
        lbpPool.setSwapEnabled(true);

        emit WeightsGraduationScheduled(startTime, endTime, endWeights);
        emit SwappingStateToggled(true);
    }

// @notice Toggles trading state in case of emergency
    function setTradingState(bool enabled) external onlyOwner {
        lbpPool.setSwapEnabled(enabled);
        emit SwappingStateToggled(enabled);
    }
}
Decentralized token launch architectures vary significantly in their capital efficiency, price discovery speed, and MEV resistance:
While batch auctions on platforms like CoW Protocol provide strong MEV protection for discrete order netting, Liquidity Bootstrapping Pools provide continuous, instant secondary market liquidity without requiring off-chain solvers.
Protocols deploying LBPs regularly monitor execution analytics and on-chain trade distributions using decentralized indexing subgraphs on The Graph and reference reliable market feeds from Chainlink.
Explore more guides and career playbooks