Loading article...
Riot Platforms repaid the remaining principal and interest on its $200 million Coinbase Credit facility on September 21, releasing bitcoin, USDC and cash collateral held in custody.
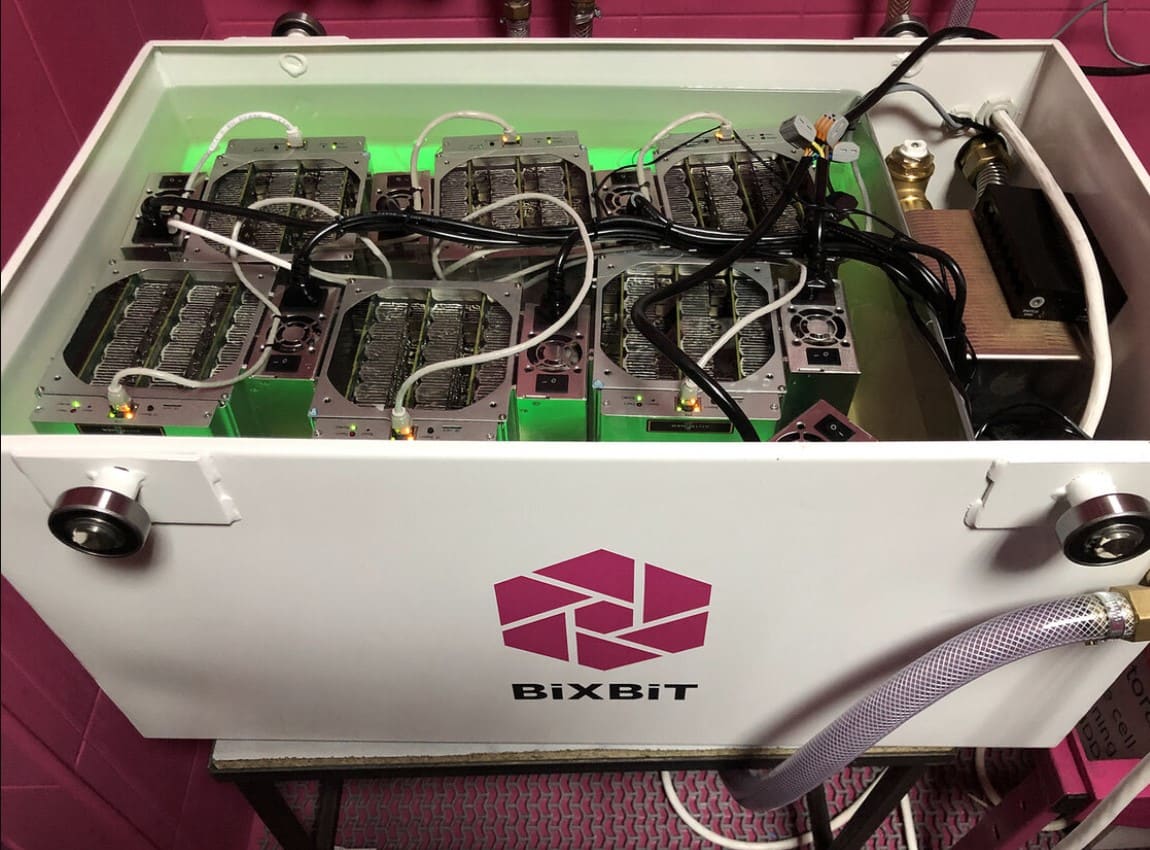
An immersion-cooling cell holding bitcoin mining hardware. Photo: Stealth2021 via Wikimedia Commons (CC BY-SA 4.0). Source
Riot Platforms (NASDAQ: RIOT) has repaid a $200 million credit facility from Coinbase Credit in full, releasing the collateral that secured it. The bitcoin miner and data-center developer completed the voluntary repayment of all outstanding principal and accrued interest on Monday, September 21, and disclosed it in a filing with the US Securities and Exchange Commission on Friday, September 25, as Cointelegraph reported.
The facility was secured by Riot's financial assets, including bitcoin, USDC and cash held in the custody of Coinbase Custody Trust Company. Those security interests were released alongside the repayment. Riot paid no early termination fee or penalty in connection with the prepayment, the filing shows.
The loan carried a fixed annual interest rate of 6.15 percent after an April 2026 amendment that extended its maturity to April 20, 2027, according to Bitcoin.com News. Riot had fully drawn the $200 million. At that rate, a balance of that size would cost about $12.3 million a year in interest.
The structure let Riot borrow cash against its treasury instead of selling coins. The company had fully drawn the $200 million, pledging bitcoin, USDC and cash with Coinbase Custody Trust as cover, according to that account. With the loan closed, that cover falls away and the coins return to Riot's free holdings.
The repayment unencumbers a large share of the company's bitcoin. As of June 30, Riot had pledged 5,821 bitcoin, worth about $340.7 million at the time, to secure the loan, Bitcoin.com News reported in the same account. That pledge covered roughly 51 percent of its total holdings of 11,380 bitcoin. The filing did not disclose how much bitcoin was pledged immediately before the loan closed.
The facility began smaller and grew. Riot first took a $100 million bitcoin-backed line in April 2025 to fund strategic initiatives and general corporate purposes, then doubled it to $200 million the next month for a one-time $1 million fee, according to that account. The original rate floated at the upper end of the federal funds target range or 3.25 percent, whichever was higher, plus 4.5 points, which set a floor of 7.75 percent a year.
Riot cleared the debt about seven months before the revised maturity date without paying a break fee. The April 2026 amendment had replaced the floating formula with the 6.15 percent fixed rate and pushed maturity to April 20, 2027, roughly a year out. The agreement's early termination fee applied only through the four-month anniversary of the original April 21, 2026 maturity, a window that closed August 21, so nothing was owed on the September repayment. The payoff also removes restrictions the credit agreement had placed on a substantial pool of collateral.
The payoff lands as Riot pushes further into data centers alongside mining. In August the company signed a 20-year lease for 191 megawatts of computing capacity at its Rockdale, Texas campus with an unnamed artificial intelligence developer, a deal Riot said should generate about $9.1 billion in revenue over its initial term. At the time, Cointelegraph described the customer only as a "leading frontier AI" company, and Bloomberg later identified it as Anthropic and put the value at about $9 billion, citing people familiar with the matter, according to Cointelegraph's loan report.
The data-center arm is already contributing. Riot posted $167.2 million in revenue for the first quarter of 2026, with the newly launched data-center business supplying $33.2 million of that total, according to Cointelegraph's May coverage as referenced in its loan report.
Coinbase's commitment to extend further credit under the facility ended with the repayment. Riot's balance sheet now carries the freed collateral with no draw outstanding against it.