Loading article...

A deep technical and financial guide to spot and futures crypto ETFs, covering institutional custody architecture, cash creation mechanics, and market impacts.
The regulatory approval and launch of spot Bitcoin and Ethereum Exchange-Traded Funds (ETFs) in the United States represented a monumental structural shift in global capital markets. For the first time in financial history, sovereign wealth funds, corporate treasuries, pension funds, registered investment advisors (RIAs), and retail investors acquired a standardized mechanism to gain direct price exposure to spot digital assets through traditional brokerage accounts without managing private keys or navigating crypto exchanges.
To understand the scope of crypto ETFs, one must evaluate how these vehicles bridge traditional institutional financial infrastructure with decentralized public blockchain networks. An ETF is not merely a tracking ticker on an exchange display; it is a complex legal, custody, and arbitrage engine governed by strict securities regulations, daily Net Asset Value (NAV) accounting, and specialized institutional custodian vaults.
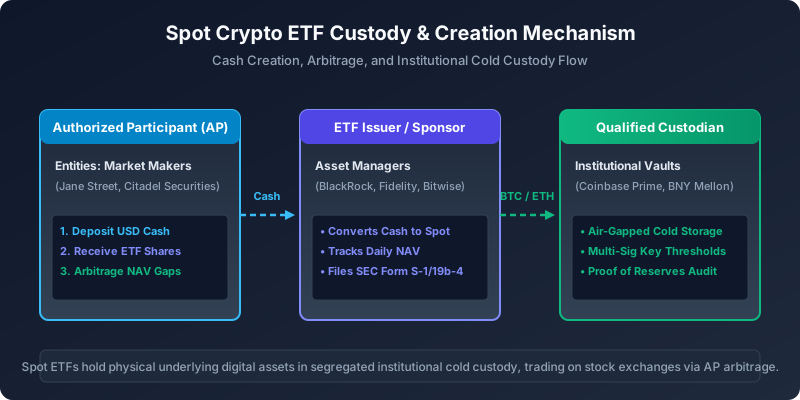
An Exchange-Traded Fund is a pooled investment vehicle traded on public stock exchanges (such as Nasdaq, Cboe BZX, and NYSE Arca) in real time throughout market hours. Unlike mutual funds, which settle only once per day after market close, ETFs trade continuously like individual equities.
Before the SEC approved spot crypto ETFs, investors were limited to Bitcoin futures ETFs (such as ProShares BITO, approved in October 2021). Understanding the fundamental differences between spot and futures funds is critical for evaluating performance and portfolio tracking efficiency.
A spot ETF holds physical digital assets directly in segregated custody wallets. When an investor buys a share of BlackRock's iShares Bitcoin Trust (IBIT) or Fidelity's Wise Origin Bitcoin Fund (FBTC), the fund sponsor acquires equivalent Bitcoin on public spot markets or through OTC desks and deposits the coins with a qualified custodian.
A futures ETF does not hold physical digital assets. Instead, it invests in regulated futures contracts traded on the Chicago Mercantile Exchange (CME).
The primary reason ETF market prices remain tightly aligned with their underlying Net Asset Value is the continuous creation and redemption process executed by Authorized Participants.
                  HIGH RETAIL DEMAND (Trading at Premium)
                                    |
            1. AP buys spot BTC and delivers cash to Sponsor
                                    |
            2. Sponsor issues new ETF Creation Unit to AP
                                    |
            3. AP sells ETF shares on Nasdaq to capture profit
                                    |
            4. Increased share supply drives price back to NAV
If intense buyer demand causes an ETF share price on Nasdaq to trade above its underlying NAV (for example, trading at $50.50 when the underlying Bitcoin per share is worth $50.00):
Conversely, if panic selling causes ETF shares to trade at a discount to NAV (such as trading at $49.50 when underlying Bitcoin per share is worth $50.00):
In traditional equity ETFs (such as Vanguard S&P 500 ETFs), creation and redemption occur "in-kind." APs deliver actual physical stock shares directly to the fund sponsor. However, for spot Bitcoin and Ethereum ETFs, the SEC mandated a Cash Creation and Redemption model due to regulatory broker-dealer constraints.
Registered U.S. broker-dealers (like Citadel or Goldman Sachs) face strict FINRA and SEC net capital rules regarding handling unregistered digital assets directly on their balance sheets. Under the cash creation framework:
Holding tens of billions of dollars worth of bearer digital assets requires military-grade security infrastructure. The loss or compromise of private keys would result in catastrophic fund losses without recourse.
Spot crypto ETF issuers rely on qualified custodians like Coinbase Prime, Fidelity Digital Assets, and BNY Mellon.
The path to U.S. spot Bitcoin ETF approval spanned over a decade, beginning with the Cameron and Tyler Winklevoss filing in July 2013 and culminating in the historical SEC approval on January 10, 2024.
To launch a new ETF, two separate regulatory filings must receive SEC clearance:
For years, the SEC rejected spot Bitcoin ETF applications citing concerns over market manipulation on offshore exchanges. The legal paradigm shifted in August 2023 when the U.S. Court of Appeals for the D.C. Circuit ruled in favor of Grayscale Investments. The court found that the SEC's arbitrary approval of Bitcoin futures ETFs while denying spot Bitcoin ETFs was unlawful under the Administrative Procedure Act, given that spot and futures prices are 99% correlated. This ruling forced the SEC to approve spot applications in January 2024.
Following Bitcoin's approval, the SEC approved spot Ethereum ETFs in May 2024. However, Ethereum spot ETFs introduced a distinct architectural compromise: the exclusion of staking yields.
Native Ethereum validator staking generates annual rewards (roughly 3.5% to 4.5%) derived from consensus rewards and transaction priority tips. However, the SEC expressed concerns that pooled staking mechanisms constituted an unregistered securities offering under the Howey Test.
To secure regulatory clearance, issuers like BlackRock, Fidelity, and Grayscale removed all staking language from their S-1 registration statements. As a result:
The launch of spot crypto ETFs represents one of the most successful product rollouts in ETF industry history. Within six months of launch, U.S. spot Bitcoin ETFs accumulated over $50 billion in cumulative assets under management (AUM).
Prior to ETFs, professional financial planners managing wealth for high-net-worth clients could not recommend self-custodied crypto or unregulated offshore exchanges due to fiduciary obligations. Spot ETFs allow RIAs to incorporate a 1% to 5% digital asset allocation directly into wealth management software like Morningstar and Envestnet.
The influx of ETF liquidity expanded institutional basis trading strategies. Hedge funds execute cash-and-carry trades by purchasing spot ETF shares while simultaneously shorting CME Bitcoin futures when futures trade at a premium. This market-neutral arbitrage generates low-risk annualized yields while cementing price alignment across traditional and crypto-native venues.
When buying crypto on an exchange like Coinbase, you own actual bearer digital assets that you can withdraw to a self-custodied wallet. When buying a spot ETF share through a brokerage (like Schwab or Fidelity), you own a financial security representing a fractional claim on assets held by the fund's custodian. You cannot withdraw physical Bitcoin or ETH from an ETF share to a personal crypto wallet.
Most major spot Bitcoin and Ethereum ETF sponsors charge expense ratios ranging between 0.12% and 0.25% annually. Many issuers offered temporary fee waivers (0.00% for the first 6 months or until reaching $5 billion in AUM) to capture initial market share.
Yes. Unlike holding crypto on a centralized exchange where funds might be commingled or subject to bankruptcy proceedings, spot ETF assets are held in segregated, bankruptcy-remote institutional custody accounts governed by strict SEC customer protection rules.
If a public blockchain undergoes a hard fork resulting in a new token chain (or distributes an airdrop), the ETF custodian takes possession of the new tokens. The ETF sponsor evaluates whether to sell the new tokens for USD cash and distribute proceeds to shareholders, or forfeit the fork if security risks exist. Shareholders do not automatically receive airdropped tokens in their brokerage accounts.
Custodians produce daily proof of reserves reports certified by independent public accounting firms. Additionally, because public blockchain ledgers are transparent, third-party blockchain intelligence entities publicly monitor and audit the specific wallet cluster addresses held by custodian institutions like Coinbase Prime and BitGo on behalf of fund sponsors.
While underlying cryptocurrencies trade 24 hours a day and 7 days a week on decentralized networks and global spot exchanges, ETF shares only trade on traditional stock exchanges during regular stock market hours. Intraday price movements occurring over the weekend are reflected when equity markets open on Monday morning.
Explore more guides and career playbooks