Loading article...

The Bank of Korea told lawmakers on Oct. 22 it will draft a Foreign Exchange Transactions Act amendment this year to regulate stablecoins as a means of payment, while a separate crypto bill and a tax fight move toward year-end.
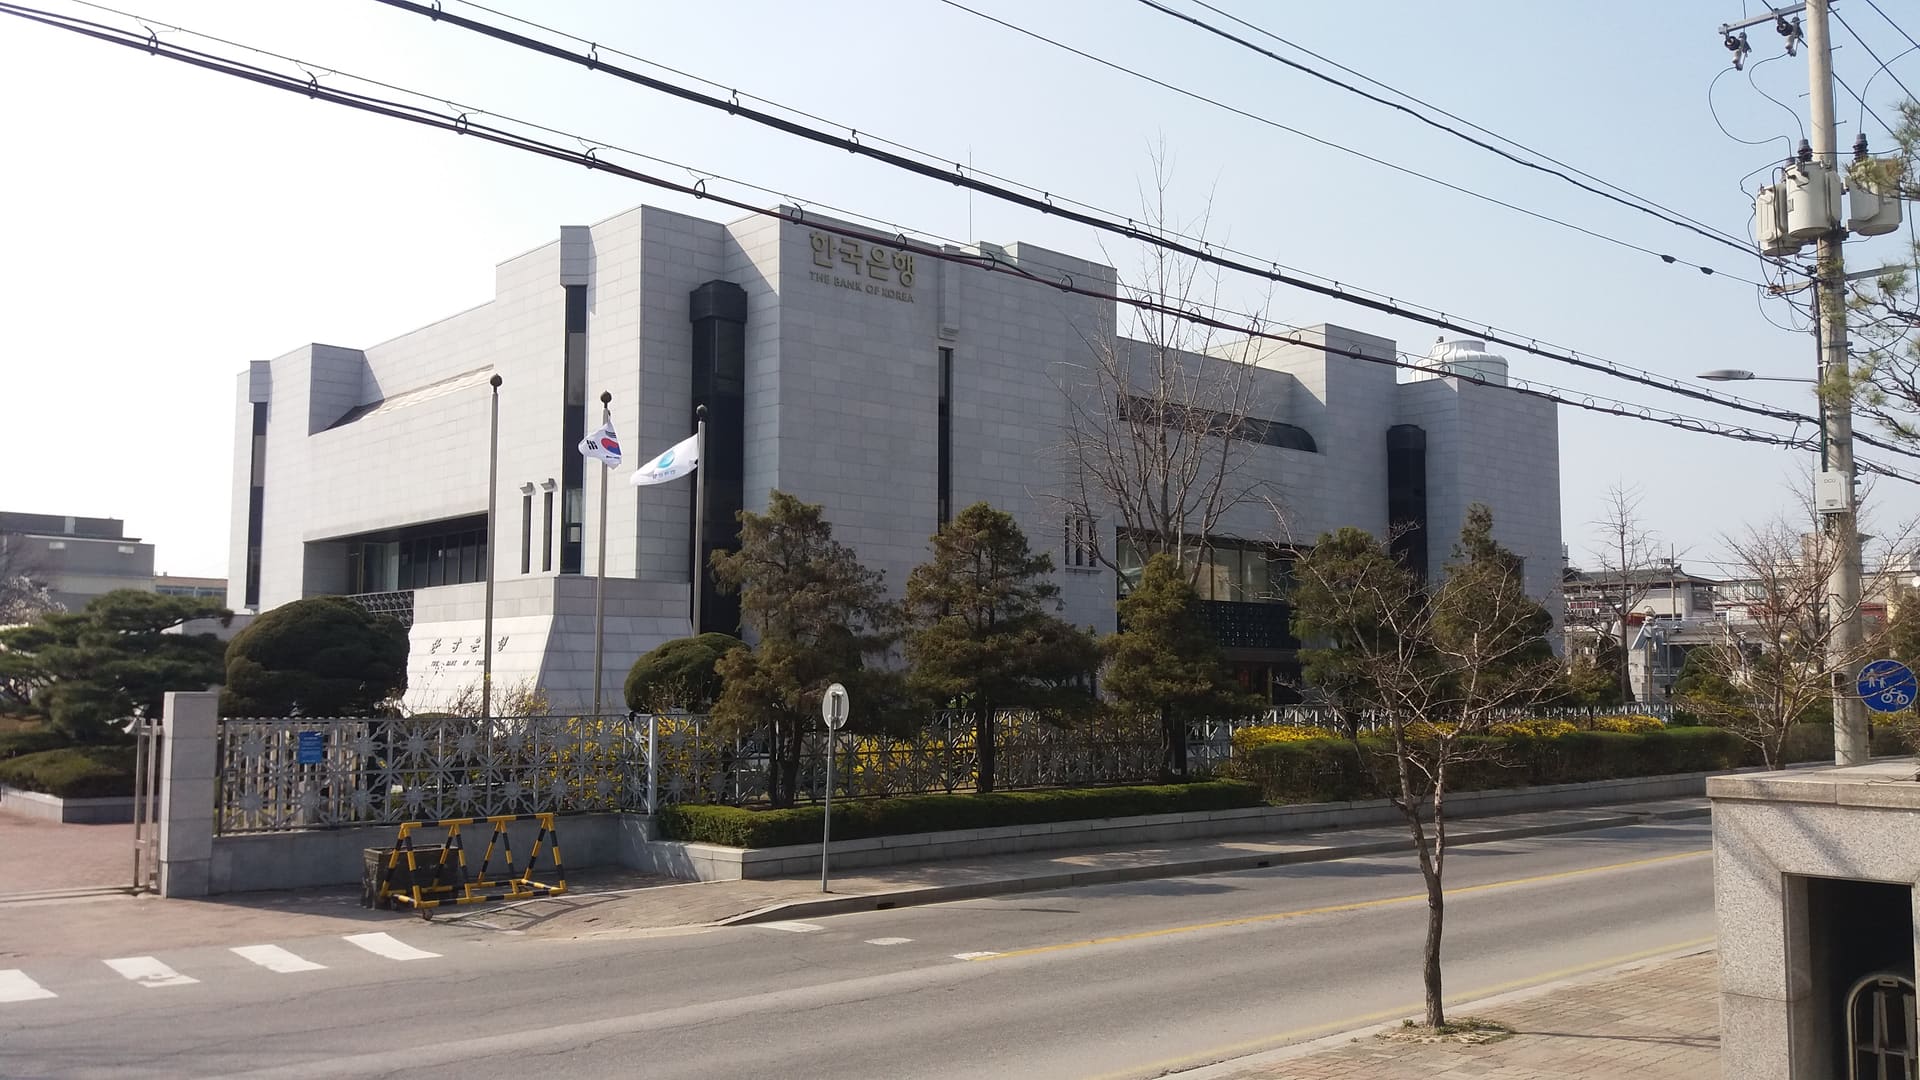
A Bank of Korea branch building in Chungbuk, South Korea. Photo: Neoalpha via Wikimedia Commons (CC0). Source
The Bank of Korea will prepare an amendment to the Foreign Exchange Transactions Act with the government this year that would regulate stablecoins as a means of payment, a written report the central bank filed for the National Assembly's annual audit on Oct. 22 shows. Korean outlet Digital Asset published the filing's contents on Oct. 23.
In that document the central bank said it is consulting with the government on measures to govern cross-border digital asset transactions and is building a monitoring system that reports through the foreign exchange network. The filing answers a remediation request lawmakers attached to last year's audit, when parliament asked the bank to widen payment infrastructure, extend large-value payment system operating hours to 8 p.m. and draw up countermeasures against money-laundering risks tied to global exchanges. The bank also said it would establish an international cooperation system to counter illegal digital asset transactions, and that it will keep working with related ministries to limit regulatory-arbitrage trades while digital asset legislation is still moving through the process.
Bitcoin Magazine described the same submission as a plan to write a bill rather than a bill itself. No draft text, no named token and no passage date have been set. The outlet also noted that means of payment is a defined term in Korean forex law, covering an instrument whose cross-border movement must be reported, which on that reading would place dollar stablecoins under the same controls as a wire transfer rather than give them legal tender status.
The bank tied the proposal to channels it said make illegal transactions easier. Digital assets can move across borders without passing through a financial institution, the filing said, and mixers, anonymity-enhancing technology and regulatory gaps around personal wallets add to the problem.
A separate amendment is already law. The National Assembly passed a Foreign Exchange Transactions Act revision on May 7 that creates a registration regime for virtual asset transfer businesses, and it was promulgated on June 2, the Ministry of Finance and Economy said. On Oct. 7 the ministry published a draft enforcement decree filling in the rules, with public comments running through Oct. 26. Both the amendment and the decree are scheduled to take effect on Dec. 3.
The draft defines the new business category as cross-border transfers between domestic and overseas virtual asset service providers, plus transfers between a domestic provider and a personal wallet. Operators must register, connect their systems to the Bank of Korea's foreign exchange information network and report transfer details, which the ministry said will be shared with the National Tax Service, Korea Customs Service, Financial Supervisory Service and the Financial Intelligence Unit. Registration rules in the draft also require at least two qualified employees per office with two years of foreign exchange experience or approved training, and no separate minimum equity capital, crypto.news reported. The outlet added that social media claims casting the decree as official payment-instrument status for USDT and USDC go beyond the ministry's text, which describes a registration and reporting framework. The same reporting said the framework could reach large exchanges such as Upbit and Bithumb where their activity meets the definition, with inspections handled by the Financial Supervisory Service.
The wider Digital Asset Basic Act, which covers exchange licensing and stablecoin issuance, sits in consultation. Financial Services Commission chairman Lee Eog-weon told lawmakers on Oct. 22 that those discussions are in their final stage and that the government will introduce the bill as soon as possible, Bitcoin Magazine reported, citing Bloomingbit.
Tax is the item with a fixed date. Korea's crypto income tax is due to take effect Jan. 1, 2027, after three postponements, and lawmakers have questioned taxing a market before the law defining it exists. Two petitions, one to repeal the tax and one to defer it by two years, have each cleared the 50,000 signatures that force a legislative review, the same report said. Democratic Party leader Kim Min-seok said on Oct. 22 that he had raised the need for a thorough final review of the plan, while Lee told lawmakers the tax should take various circumstances into full consideration.
The National Tax Service plans to finalize its draft tax notice by Oct. 30, Bitcoin Magazine reported.