Loading article...

A comprehensive technical guide to cryptocurrency token swaps, exploring Automated Market Maker (AMM) formulas, DEX aggregation, MEV protection, and cross-chain HTLC atomic swap mechanics.
In Decentralized Finance (DeFi), a token swap refers to the peer-to-peer exchange of one cryptocurrency asset for another directly via automated smart contracts without relying on a centralized intermediary or custodial order book. Token swaps form the primary operational engine of the Web3 economy, enabling users to rebalance portfolios, access protocol utility tokens, supply liquidity, and participate in decentralized governance across permissionless blockchain networks.
Unlike traditional financial markets where centralized brokerages hold customer assets and settle trades off-chain across multi-day settlement windows, Web3 token swaps execute atomically on-chain. Either both sides of the trade complete successfully within a single block, or the entire transaction reverts, leaving user funds safely inside their non-custodial wallets.
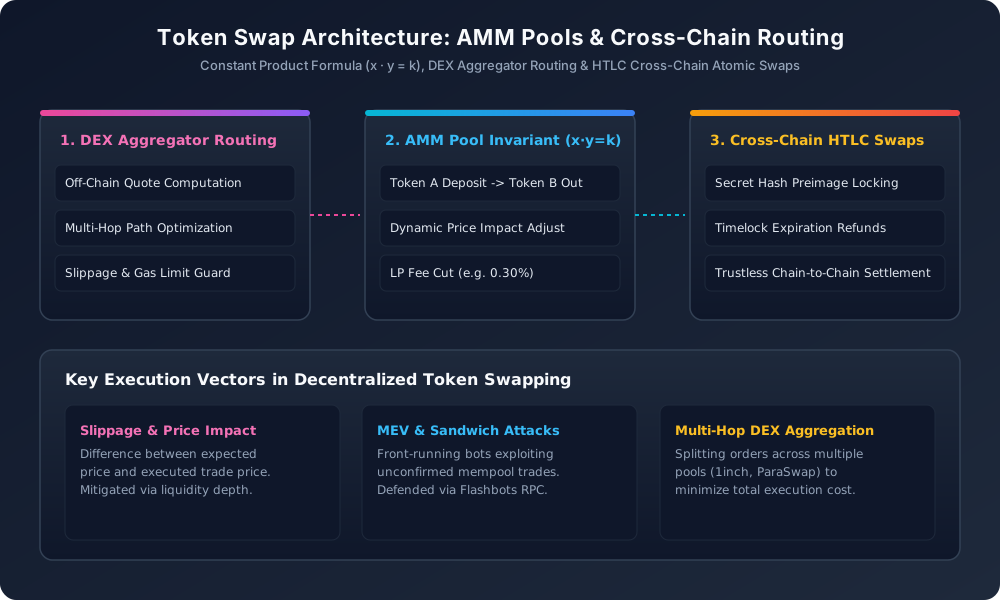
Understanding the engineering mechanics of token swaps requires contrasting them with traditional centralized exchanges (CEXs) and legacy brokerage models.
Modern decentralized exchanges - such as Uniswap, Sushiswap, and Curve - utilize Automated Market Makers (AMMs) to enable instant, continuous asset swaps without requiring an active counterparty for every individual trade order.
The foundational mathematical algorithm powering most spot token swaps is the Constant Product Formula, first popularized by Uniswap:
$$x \cdot y = k$$
Where:
As trade size increases relative to the total liquidity depth in an AMM pool, the executed price diverges from the initial spot price - a phenomenon known as Price Impact.
// Simplified Solidity AMM Swap Execution Pattern
// SPDX-License-Identifier: MIT
pragma solidity ^0.8.20;

import "@openzeppelin/contracts/token/ERC20/IERC20.sol";

contract SimpleAMMPool {
    IERC20 public immutable tokenA;
    IERC20 public immutable tokenB;

    uint256 public reserveA;
    uint256 public reserveB;

    uint256 public constant FEE_DENOMINATOR = 1000;
    uint256 public constant FEE_NUMERATOR = 997; // 0.3% trading fee

    event Swap(address indexed sender, uint256 amountIn, uint256 amountOut, address tokenIn);

    constructor(address _tokenA, address _tokenB) {
        tokenA = IERC20(_tokenA);
        tokenB = IERC20(_tokenB);
    }

    function swapTokenAForTokenB(uint256 amountAIn, uint256 minAmountBOut) external returns (uint256 amountBOut) {
        require(amountAIn > 0, "AMM: Insufficient input");

/ Transfer Token A from user to pool
        tokenA.transferFrom(msg.sender, address(this), amountAIn);

/ Apply 0.3% fee to input amount
        uint256 amountAInWithFee = amountAIn * FEE_NUMERATOR;

/ Compute output Token B amount preserving invariant k
        uint256 numerator = amountAInWithFee * reserveB;
        uint256 denominator = (reserveA * FEE_DENOMINATOR) + amountAInWithFee;
        amountBOut = numerator / denominator;

        require(amountBOut >= minAmountBOut, "AMM: Excessive slippage");

/ Update internal reserve state
        reserveA += amountAIn;
        reserveB -= amountBOut;

/ Transfer Token B to user
        tokenB.transfer(msg.sender, amountBOut);

        emit Swap(msg.sender, amountAIn, amountBOut, address(tokenA));
    }
}
Liquidity in Web3 is fragmented across dozens of decentralized exchanges and thousands of isolated liquidity pools. DEX Aggregators (such as 1inch, ParaSwap, and Matcha) optimize trade execution by splitting single swap orders across multiple pools and routing trades through intermediary tokens.
DEX aggregators use advanced graph search algorithms (such as Modified Dijkstra's Algorithm or Bellman-Ford Shortest Path) off-chain to evaluate thousands of potential swap routes in real-time before constructing a single, gas-optimized smart contract execution payload for the user's wallet.
Executing public token swaps on transparent blockchain networks exposes transactions to Maximal Extractable Value (MEV) bots operating in public mempools.
Advanced decentralized exchanges optimize capital efficiency using Concentrated Liquidity. Instead of distributing liquidity evenly across the virtual curve from zero to infinity ($0, \infty$), liquidity providers bound their capital within specific upper ($p_b$) and lower ($p_a$) price ticks:
$$L = \frac{\Delta y}{\Delta \sqrt{p}} = \frac{\Delta x}{\Delta \left( \frac{1}{\sqrt{p}} \right)}$$
$$\text{Virtual Reserve Equation:} \quad \left( x + \frac{L}{\sqrt{p_b}} \right) \left( y + L \cdot \sqrt{p_a} \right) = L^2$$
Concentrated liquidity allows capital efficiency gains of up to $4,000\times$ compared to standard Uniswap v2 pools, allowing small reserves to absorb large swaps with minimal price impact.
To understand how DEX aggregators compute optimal multi-hop swap routes off-chain before submitting smart contract payload calls, inspect the following graph pathfinding module:
import heapq
from typing import Dict, List, Tuple

class DEXGraphRouter:
    def __init__(self):
        # Adjacency list: Graph[token_a][token_b] = (exchange_rate, pool_address, gas_cost)
        self.graph: Dict[str, Dict[str, List[Tuple[float, str, int]]]] = {}

    def add_pool(self, token_a: str, token_b: str, rate_a_to_b: float, pool: str, gas: int):
        if token_a not in self.graph:
            self.graph[token_a] = {}
        if token_b not in self.graph[token_a]:
            self.graph[token_a][token_b] = []
        self.graph[token_a][token_b].append((rate_a_to_b, pool, gas))

    def find_best_route(self, start_token: str, end_token: str, max_hops: int = 3) -> Tuple[float, List[str]]:
        # Max-heap priority queue storing (-accumulated_rate, current_token, path_history)
        queue = [(-1.0, start_token, [start_token])]
        best_rate = 0.0
        best_path = []

        while queue:
            neg_rate, current, path = heapq.heappop(queue)
            current_rate = -neg_rate

            if current == end_token:
                if current_rate > best_rate:
                    best_rate = current_rate
                    best_path = path
                continue

            if len(path) > max_hops:
                continue

            if current in self.graph:
                for neighbor, pools in self.graph[current].items():
                    if neighbor not in path: # Avoid cycles
                        for rate, pool_addr, gas in pools:
                            next_rate = current_rate * rate
                            heapq.heappush(queue, (-next_rate, neighbor, path + [neighbor]))

        return best_rate, best_path

# Example Graph Router Execution
router = DEXGraphRouter()
router.add_pool("USDC", "WETH", 0.00033, "0x_uniswap_usdc_weth", 100000)
router.add_pool("WETH", "UNI", 320.0, "0x_sushiswap_weth_uni", 120000)
router.add_pool("USDC", "DAI", 1.0, "0x_curve_usdc_dai", 80000)
router.add_pool("DAI", "UNI", 0.105, "0x_uniswap_dai_uni", 110000)

rate, path = router.find_best_route("USDC", "UNI")
print(f"Optimal Multi-Hop Swap Path: {' -> '.join(path)}")
print(f"Effective Execution Rate: 1 USDC = {rate:.4f} UNI")
While standard DEX swaps execute on a single blockchain, Cross-Chain Atomic Swaps enable trustless asset exchanges between completely independent ledgers (e.g., swapping native Bitcoin for native Ethereum) without wrapped tokens or centralized bridges.
HTLC contracts enforce atomicity using two cryptographic conditions:
As token swapping infrastructure forms the backbone of crypto market liquidity, protocol development teams actively hire specialized engineers, quantitative researchers, and security auditors.
When interviewing for DEX engineering positions:
Check-Effects-Interactions pattern) is essential for DEX security.As MEV extraction on public mempools escalated, the Web3 industry shifted toward Intent-Based Architecture (pioneered by protocols like CoW Swap and UniswapX).
AMM liquidity pools remain balanced across global markets due to automated arbitrageurs utilizing Flash Loans.
// SPDX-License-Identifier: MIT
pragma solidity ^0.8.20;

interface IFlashLoanReceiver {
    function executeOperation(
        address asset,
        uint256 amount,
        uint256 premium,
        address initiator,
        bytes calldata params
    ) external returns (bool);
}

contract FlashLoanArbitrage is IFlashLoanReceiver {
    address public immutable poolProvider;

    constructor(address _poolProvider) {
        poolProvider = _poolProvider;
    }

    function executeOperation(
        address asset,
        uint256 amount,
        uint256 premium,
        address initiator,
        bytes calldata params
    ) external override returns (bool) {
/ 1. Swap borrowed asset on DEX A (where price is higher)
/ 2. Swap output back to original asset on DEX B (where price is lower)
/ 3. Repay flash loan + premium fee to lending pool
/ 4. Retain net arbitrage profit in contract

        uint256 amountToRepay = amount + premium;
        IERC20(asset).approve(poolProvider, amountToRepay);
        return true;
    }
}
Flash loans allow arbitrageurs to borrow millions of dollars in capital without upfront collateral, provided the borrowed amount plus fee is returned within the exact same atomic transaction block. This mechanism ensures that asset prices across Uniswap, Sushiswap, Curve, and Binance remain tightly pegged to global market fair value.
For protocol engineers and Web3 developers designing or integrating swap systems:
minAmountOut) in smart contract calls to prevent transaction exploitation during market volatility.While the Constant Product formula ($x \cdot y = k$) works effectively for volatile asset pairs (like ETH/USDC), it creates excessive slippage when swapping assets pegged to the same target value (such as USDC/USDT or stETH/ETH). To solve this, Curve Finance introduced the Stableswap Invariant, combining a constant sum model with a constant product model:
$$A n^n \sum x_i + D = A D n^n + \frac{D^{n+1}}{n^n \prod x_i}$$
Where $A$ is an amplification coefficient governing how closely the curve flatlines near $1:1$ parity, $n$ is the number of assets in the pool, and $D$ is the total invariant pool depth. By flattening the bonding curve within normal trading bands, the Stableswap invariant enables ultra-low slippage swaps for millions of dollars in stablecoins.
Understanding the technical architecture of token swaps provides foundational insight into how decentralized financial markets operate without intermediaries, delivering secure, transparent, and global financial access.
Explore more guides and career playbooks