Loading article...

An in-depth technical and legal guide to real-world asset (RWA) real estate tokenization, ERC-3643 smart contracts, SPV legal wrappers, and emerging career opportunities.
Real estate represents the largest single asset class in the global economy, valued at over $300 trillion. Despite its immense market size, physical real estate remains plagued by extreme illiquidity, high transaction friction, opaque title registries, and elevated barriers to entry. Traditional property acquisitions require lengthy closing windows (often 60 to 90 days), substantial capital reserves for down payments, expensive legal retainers, title insurance fees, and regional regulatory compliance overhead.
The emergence of Web3 technology and Real-World Asset (RWA) tokenization is transforming how property ownership is structured, financed, and traded. By converting physical property titles into programmable, permissioned digital security tokens on public blockchain networks such as Ethereum and Polygon, real estate tokenization enables fractional ownership, instant cross-border settlement, automated dividend distribution, and integration into decentralized lending protocols.
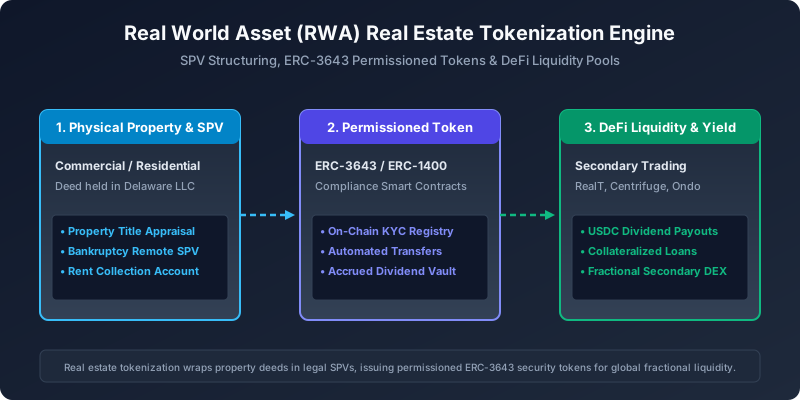
Tokenizing physical property is not as simple as deploying an ERC-20 smart contract on a blockchain. Blockchains cannot enforce physical rights directly; they enforce code execution rules. Therefore, tokenizing real estate requires a hybrid legal-technical architecture that bridges physical property jurisdiction laws with smart contract execution.
Directly recording property deeds on a blockchain is currently restricted in most legal jurisdictions because municipal property registries require traditional legal deeds. Tokenization platforms overcome this limitation using a Special Purpose Vehicle (SPV), typically organized as a bankruptcy-remote Limited Liability Company (LLC) or Private Limited Company.
Standard ERC-20 tokens are permissionless; anyone can transfer ERC-20 tokens to any wallet address without restriction. However, security tokenized real estate assets must comply with strict securities laws (such as SEC Regulation D, Regulation S, or MiCA in Europe), which require investor accreditation checks, Know Your Customer (KYC) verification, and Anti-Money Laundering (AML) screening.
The ERC-3643 standard (formerly known as T-REX, Token for Regulated EXchanges) has emerged as the industry benchmark for real-world asset tokenization.
// SPDX-License-Identifier: MIT
pragma solidity ^0.8.20;

interface IERC3643 {
/ Identity Registry checking investor KYC status before execution
    function identityRegistry() external view returns (address);
    function compliance() external view returns (address);

/ Conditional transfer function checking identity and compliance
    function transfer(address to, uint256 amount) external returns (bool);
    function forcedTransfer(address from, address to, uint256 amount) external returns (bool);
    function freezePartialTokens(address userAddress, uint256 amount) external;
}
The execution lifecycle of a real estate tokenization project spans four sequential phases: asset sourcing, legal tokenization, primary distribution, and secondary liquidity management.
[ Phase 1: Property Sourcing ] -> [ Phase 2: SPV & Smart Contracts ]
                                                 |
[ Phase 4: Secondary Trading ] <- [ Phase 3: Primary Token Sale ]
As real estate tokenization accelerates toward trillion-dollar adoption, specialized career opportunities are expanding across software engineering, legal compliance, asset management, and DeFi risk architecture.
Smart contract engineers building RWA platforms require deep knowledge of Solidity, EVM memory architecture, and permissioned token standards like ERC-3643 and ERC-1400.
Because tokenized properties represent registered or exempt securities, legal professionals with expertise in both traditional real estate law and digital asset regulations are highly sought after.
Managing a tokenized real estate portfolio requires traditional real estate asset management skills paired with Web3 operational literacy.
The true power of tokenized real estate is unlocked when security tokens can be utilized as productive collateral across decentralized finance protocols.
Below is a production-grade Solidity smart contract demonstrating how rental income collected in USDC is distributed proportionally to real estate token holders.
// SPDX-License-Identifier: MIT
pragma solidity ^0.8.20;

import "@openzeppelin/contracts/token/ERC20/IERC20.sol";
import "@openzeppelin/contracts/access/Ownable.sol";
import "@openzeppelin/contracts/utils/ReentrancyGuard.sol";

interface IERC3643Permissioned {
    function balanceOf(address account) external view returns (uint256);
    function totalSupply() external view returns (uint256);
}

contract RealEstateDividendVault is Ownable, ReentrancyGuard {
    IERC3643Permissioned public immutable propertyToken;
    IERC20 public immutable usdcToken;

    uint256 public totalDividendsDeposited;
    mapping(address => uint256) public lastClaimedDividendPerToken;
    uint256 public dividendPerTokenStored;

    event DividendDeposited(uint256 amount, uint256 newDividendPerToken);
    event DividendClaimed(address indexed investor, uint256 amount);

    constructor(address _propertyToken, address _usdcToken) Ownable(msg.sender) {
        propertyToken = IERC3643Permissioned(_propertyToken);
        usdcToken = IERC20(_usdcToken);
    }

// @notice Deposit monthly rental income in USDC to be distributed to token holders
    function depositRentalIncome(uint256 _amount) external onlyOwner {
        require(_amount > 0, "Deposit must be greater than zero");
        uint256 totalTokens = propertyToken.totalSupply();
        require(totalTokens > 0, "No property tokens minted");

        usdcToken.transferFrom(msg.sender, address(this), _amount);
        totalDividendsDeposited += _amount;

/ Scale by 1e18 to prevent precision loss during division
        dividendPerTokenStored += (_amount * 1e18) / totalTokens;

        emit DividendDeposited(_amount, dividendPerTokenStored);
    }

// @notice Calculate pending unclaimed rental dividends for an investor
    function getPendingDividends(address _investor) public view returns (uint256) {
        uint256 userBalance = propertyToken.balanceOf(_investor);
        if (userBalance == 0) return 0;

        uint256 dividendDiff = dividendPerTokenStored - lastClaimedDividendPerToken[_investor];
        return (userBalance * dividendDiff) / 1e18;
    }

// @notice Claim accumulated rental income dividends in USDC
    function claimDividends() external nonReentrant {
        uint256 pending = getPendingDividends(msg.sender);
        require(pending > 0, "No dividends available to claim");

        lastClaimedDividendPerToken[msg.sender] = dividendPerTokenStored;
        require(usdcToken.transfer(msg.sender, pending), "USDC transfer failed");

        emit DividendClaimed(msg.sender, pending);
    }
}
Several pioneering protocols and platforms have successfully tokenized real estate assets, establishing proof of concept for global adoption.
RealT is a market pioneer in fractional real estate tokenization. The platform tokenizes single-family residential properties located across the United States. Investors acquire ERC-20 tokens representing shares in the property's owning LLC and receive daily rental income payments in xDAI or USDC sent directly to their self-custodied Ethereum wallets.
Centrifuge allows originators to tokenize real-world assets, such as mortgages, commercial real estate loans, and invoices, into non-fungible tokens (NFTs). These NFTs are placed into collateralized financing pools where investors fund senior and junior tranches using stablecoins, unlocking institutional capital for real estate developers.
Despite its immense growth potential, real estate tokenization faces structural challenges that developers, legal experts, and investors must address.
Securities regulations vary dramatically across jurisdictions. A security token compliant with US SEC Regulation D may not meet regulatory standards under the European Union's Markets in Crypto-Assets (MiCA) framework or the Swiss Financial Market Supervisory Authority (FINMA). Establishing cross-border interoperability requires complex multi-jurisdictional legal structuring.
While smart contracts operate flawlessly on-chain, physical real estate requires real-world maintenance: roof repairs, tenant evictions, property tax assessments, and natural disaster insurance claims. If a physical tenant defaults on rent or damages a property, smart contracts cannot automatically resolve the physical dispute. Operations rely heavily on trusted traditional property management companies.
Although tokenization enables fractional ownership, secondary market liquidity for individual property security tokens remains limited compared to major cryptocurrencies like Bitcoin or liquid equities like Apple stock. Platforms utilize automated market maker (AMM) liquidity pools and institutional market makers to improve secondary trading volumes.
For professionals seeking to build a career in Web3 real estate tokenization, follow this strategic action plan:
Study the source code of the ERC-3643 T-REX open-source repository. Understand how identity registries, claim issuers, and compliance contracts interact with ERC-20 tokens to enforce whitelisting rules.
Create an open-source GitHub repository demonstrating a complete real estate tokenization workflow:
Apply directly to specialized Web3 real estate and RWA tokenization platforms:
It depends on the legal structure of the offering. In the United States, primary sales under SEC Regulation D are restricted to accredited investors. However, offerings conducted under Regulation S allow non-US international retail investors to participate, provided they pass required ONCHAINID KYC and AML verification checks.
Rental income collected from physical tenants in USD cash is converted to stablecoins (typically USDC) by the property management entity. The stablecoins are deposited into a dividend vault smart contract. Token holders can call the claimDividends() function at any time to stream their proportional rental share directly to their connected Web3 wallet.
If the property management entity sells the underlying physical real estate, the sale proceeds (minus mortgage pay-offs and closing costs) are deposited into the smart contract escrow. The permissioned property tokens are burned, and token holders receive their proportional share of the net sale proceeds in USDC.
Yes. Emerging RWA protocols allow whitelisted investors to lock their permissioned real estate security tokens into lending vaults (such as Centrifuge or Ondo) to borrow stablecoins against their physical property equity without selling their underlying shares.
Explore more guides and career playbooks